Dollar, yields sink as US Treasury to intervene in bond markets
Jamie Dutta >
Jamie Dutta >
Jamie Dutta is a Market Analyst for Vantage. He comes with extensive experience as a full-time trader and financial market commentator, having worked as a trader in top tier investment banks and trading houses.
 Updated Thu, 2026 August 20 05:04

- US to double buybacks of long-term government debt, yields decline
- Fed minutes show many officials said rate hikes may be needed
- UK inflation edges higher in July but not seen altering rate perceptions
- Moderna soars 160% on cancer vaccine trial promise, burning shorts
- Gold and Bitcoin pop higher as USD sinks below 200-day SMA
Forex
USD tanked just before the start of the US session hitting a three-month bottom. The Dollar Index settled close to its lows for the day and below the 200-day SMA at 99.17. Washington stepped in to stop the bond market sell-off which had caused long-end 30-year Treasury yields to hit multi-decade highs. Concerns were rising about a buyers’ strike, bond vigilantes and a dysfunctional bond market. The Treasury said it would at least double buyback operations for long-dated bonds causing yields to tumble. Support sits at the midpoint of the 2026 low to high move at 98.67. The Fed minutes sparked little reaction.
EUR jumped to fresh cycle highs and through the 200-day SMA at 1.1627 on the back of the dollar sell-off and bond market volatility. Eurozone final CPI was left unrevised at 2.9% in July while core CPI was also held at 2.5%. There was little evidence that energy was contributing to broader price gains. However, a September rate hike is virtually fully priced by money markets. Mid to upper 1.17s a re a bull target, though prices are mildly overbought.
GBP hit three and a half month highs and resistance at the early May peaks around 1.3652/57. Earlier in the day, we got a rise in UK CPI as widely expected, though food inflation, which the Bank of England tracks closely, remained quite benign. The BoE’s core services measure of inflation did pick up a little to 3.8%, but probably not enough to trouble rate setters on the MPC. They remain divided, watching relatively soft domestic inflation and rising energy and crude prices.
JPY strengthened as Treasury yields slid, taking with the major back to the 200-day SMA at 158.24. As we hinted, the continued trade around the long-term upward trendline around 159.45 eventually has acted as resistance. Strong Core machinery orders, rising 9.7% in June, added a little to overnight momentum as market expectations for a September BoJ rate hike continue to consolidate.
Stocks
US stocks: The S&P 500 added 0.22% to close at 7,708. The Nasdaq closed down 0.22% at 29,426. The Dow Jones settled higher by 0.22% at 5`3,468. There was mixed sector performance with Healthcare the biggest winner, with Consumer Discretionary and Materials next best. Industrials, Tech and Financials were the main laggards. Health was buoyed by Moderna surging more than 176% after a cancer breakthrough drug trial with Merck, which rose 11% and hit a record high. Marvell climbed 10% as the chip maker said it has issued Google a warrant to purchase up to 59 million shares, or a stake in the company worth $12.2 billion. Estee Lauder gained 16% on strong results with quarterly metrics beating expectations and full-year outlook lifted.
Asian Stocks: Futures are mixed. APAC stocks were mostly lower on tech selling on Wall Street and elevated bond yields. The ASX 200 eased on earnings and hawkish RBA speak. The Nikkei 225 was lower on tech weakness too, even as JGB yields pulled back. The Hang Seng and Shanghai Comp were mixed with Hong Kong earnings from Baidu and Xiaomi while the mainland was downbeat.
Gold
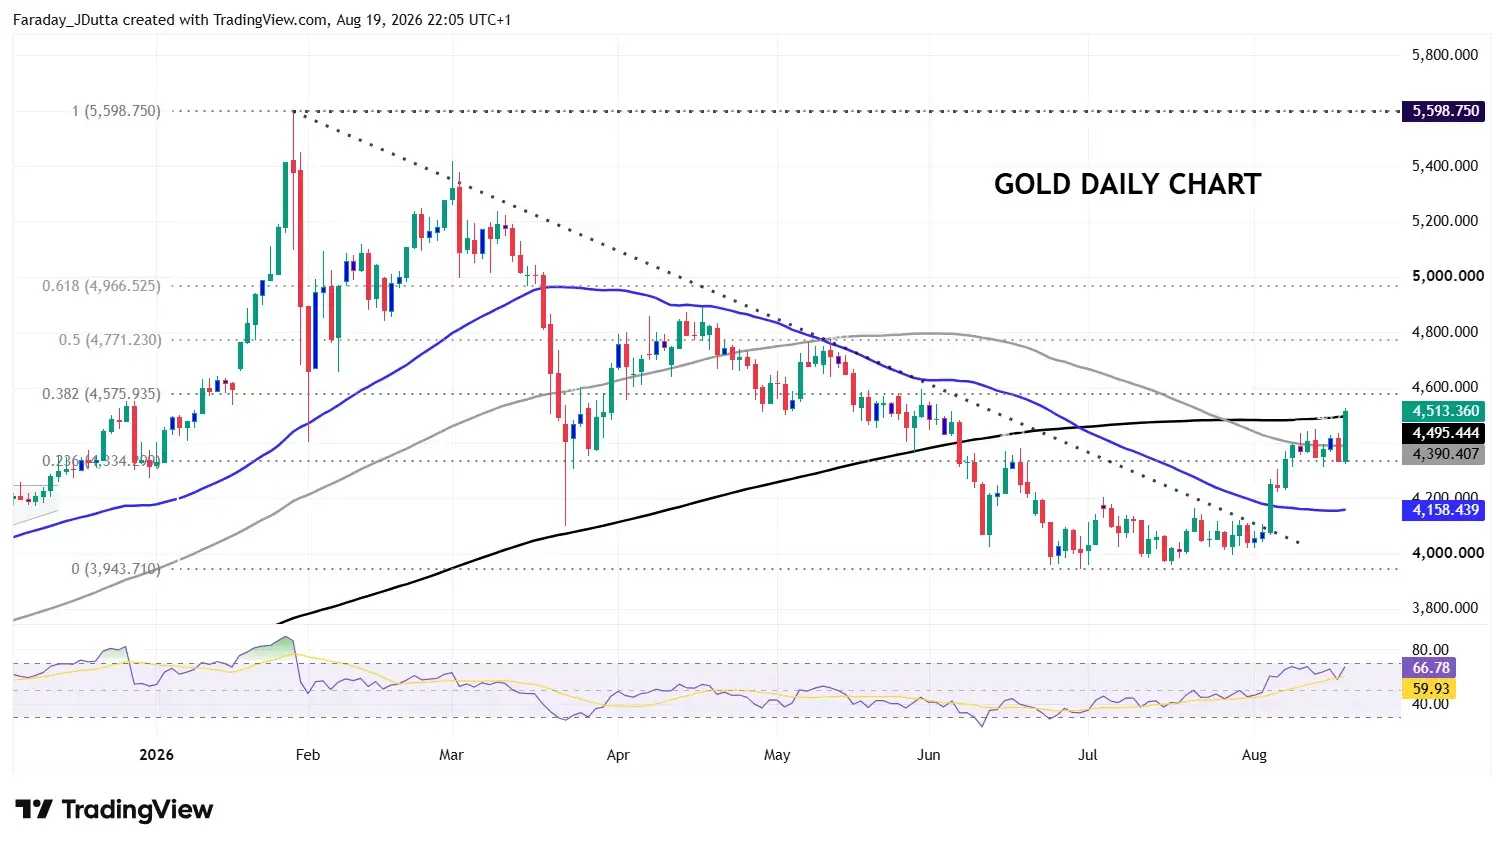
Gold broke to the upside after classic consolidation around $4,500. Prices hit the 200-day SMA at $4,495 as long-end bond yields tumbled after action by the US Treasury. See below for more.
Chart of the Day – Gold upside breakout
Gold had been tracking sideways in recent sessions around the 100-day SMA at $4,390 and a minor Fib level $4,334. That came after rebounding sharply from July lows near $3,900. Prices then broke the medium-term downward trendline from the record high just below $5,600. The move has been supported by a weaker US dollar and growing market conviction that the Fed is close to the end of its tightening cycle, reducing the headwind from higher interest rates. September rate hikes bets have fallen from a fully priced move to around a one-in-three chance. Ongoing geopolitical tensions in the Middle East have also continued to underpin investor demand. Yesterday’s upside breakout has hit the 200-day SMA at $4,495, with a major Fib level (38.2%) of the high to low 2026 move at $4,575. The midpoint sits at $4,771.