Crude and yields jump, hindering stock’s record rally
Jamie Dutta >
Jamie Dutta >
Jamie Dutta is a Market Analyst for Vantage. He comes with extensive experience as a full-time trader and financial market commentator, having worked as a trader in top tier investment banks and trading houses.
 Updated Tue, 2026 August 11 04:34
- President Trump lashes out after Iranian demands, with deal hopes dimming
- Dollar steadies after NFP dip as markets eye US CPI
- World’s biggest chipmaker TSMC’s sales surge 45% amid buoyant AI demand
- SpaceX stock rebounds above $135 IPO price after 23% gain last week
Forex
USD consolidated around recent lows after its breakdown at the end of July. The Dollar Index is trading around the 100-day SMA at 99.73 with the 200-day below at 99.18. Markets digested Friday’s weak NFP report versus stalling US-Iran peace talks, which saw Iran demand a lot more for any reopening of the Strait of Hormuz. Big downward revisions to May and June job figures means the three-month average payrolls growth is now only 20k. People leaving the workforce has seen the participation rate fall to the lowest in five years. It’s certainly a ‘no hire, no fire’ environment though there’s still a decent chance (47%) of a September Fed rate hike. Focus is on CPI and PPI this week.
EUR traded just below its 100-day SMA at 1.1567 with little specific euro region news or drivers. August is typically a quiet month for ECB communication, with a rate hike likely next month. Last week’s high at 1.1580, a near 10-week peak needs to be beaten to see 1.16 and above. The 200-day SMA resides at 1.1626.
GBP outperformed its peers as cable hit a three-week high, breaking to the upside and close to the mid-July highs at 1.3557 before paring gains late on. There’s not too much on the data calendar this week apart from Thursday’s Q2 GDP which could highlight the seasonal nature of the UK economy at present. Otherwise, the recovery in sterling sentiment is important for current strength.
JPY was the big underperformer as the major pushed up through the 200-day SMA at 158.05 and a long-term swing high from January 2025 at 158.87. A late push saw it also close above a long-term upward trendline. The weakness is slightly surprising, given the recent narrowing in yield spreads that followed Friday’s disappointing US payrolls release. The problem seems to be the inevitable bias to rebuild yen shorts after an intervention episode, even one as big as we have seen recently. Hawkish BOJ minutes didn’t help the yen so a big repricing of Fed tightening appears to be needed to add to the intervention downtrend.
Stocks
US stocks: The S&P 500 lost 0.05% to close at 7,753, the Nasdaq closed down 0.34% at 29,622 and the Dow Jones settled lower by 0.11% at 5`3,976. Sector performance was mixed with Real Estate, Utilities and Tech the clear laggards, while Energy was the big winner as crude prices jumped over 6%. Healthcare, Communication Services and Materials were also bid. The broad-based S&P 500 closed its best week since April after the NFP report. JP Morgan lifted their 2026 year-end target to 8,000 from 7,800, which implies 3.1% upside from Friday’s close. For what it’s worth, that’s now 800pts of upward revision since March by the investment bank. Intel fell over 4% after it announced a proposed $15bn common stock offering. Apple slid 1.6% after it was downgraded by a broker due to the cancelled all-glass iPhone and soaring memory costs. SpaceX continued its rebound after last week’s 23% jump. Elon Musk said the next-gen Starlink satellites could deliver more than 100x bandwidth than currently with version two.
Asian Stocks: Futures are mixed. APAC stocks were mixed though mostly higher after the soft US jobs report reined in Fed rate hike bets. The ASX 200 sold off dragged down by financials and Westpac earnings. The RBA is next up. The Nikkei 225 rallied as markets digested solid earnings. The Hang Seng and Shanghai Comp were positive though mainland gains were limited by softer CPI and PPI figures.
Gold rose in spite of higher yields and dollar for a second straight day as bugs tried to build on the strong upside breakout week. Bull targets include the 200-day SMA at 4,482 and a major Fib retracement level at 4,575.
Day Ahead – RBA Meeting
The Aussie cash rate is set to be left unchanged at 4.35%. The RBA will also release its quarterly Statement on Monetary Policy, including its latest economic projections. As a reminder, the bank paused at its last meeting in June, as expected, following three straight rate hikes at prior meetings, although the language remained hawkish as it warned of potential further rate hikes if necessary, citing persistent inflation and oil supply disruptions. The RBA also said the latest data indicated that headline and underlying inflation remained too high.
Last week’s inflation data saw price pressures ease moderately with the trimmed mean inflation metric, the RBA’s favourite, coming in two-tenths below their estimate at 3.6%. Of course, that’s still above the 2 to 3% medium-term target. Recent jobs data have also been encouraging, with the headline June print topping forecasts at 76.3k against the expected 15k, with the prior of 40.3k. The unemployment rate stayed steady at 4.4%, which all suggests there is room to sit on hands on policy.
Chart of the Day – AUD/USD rising
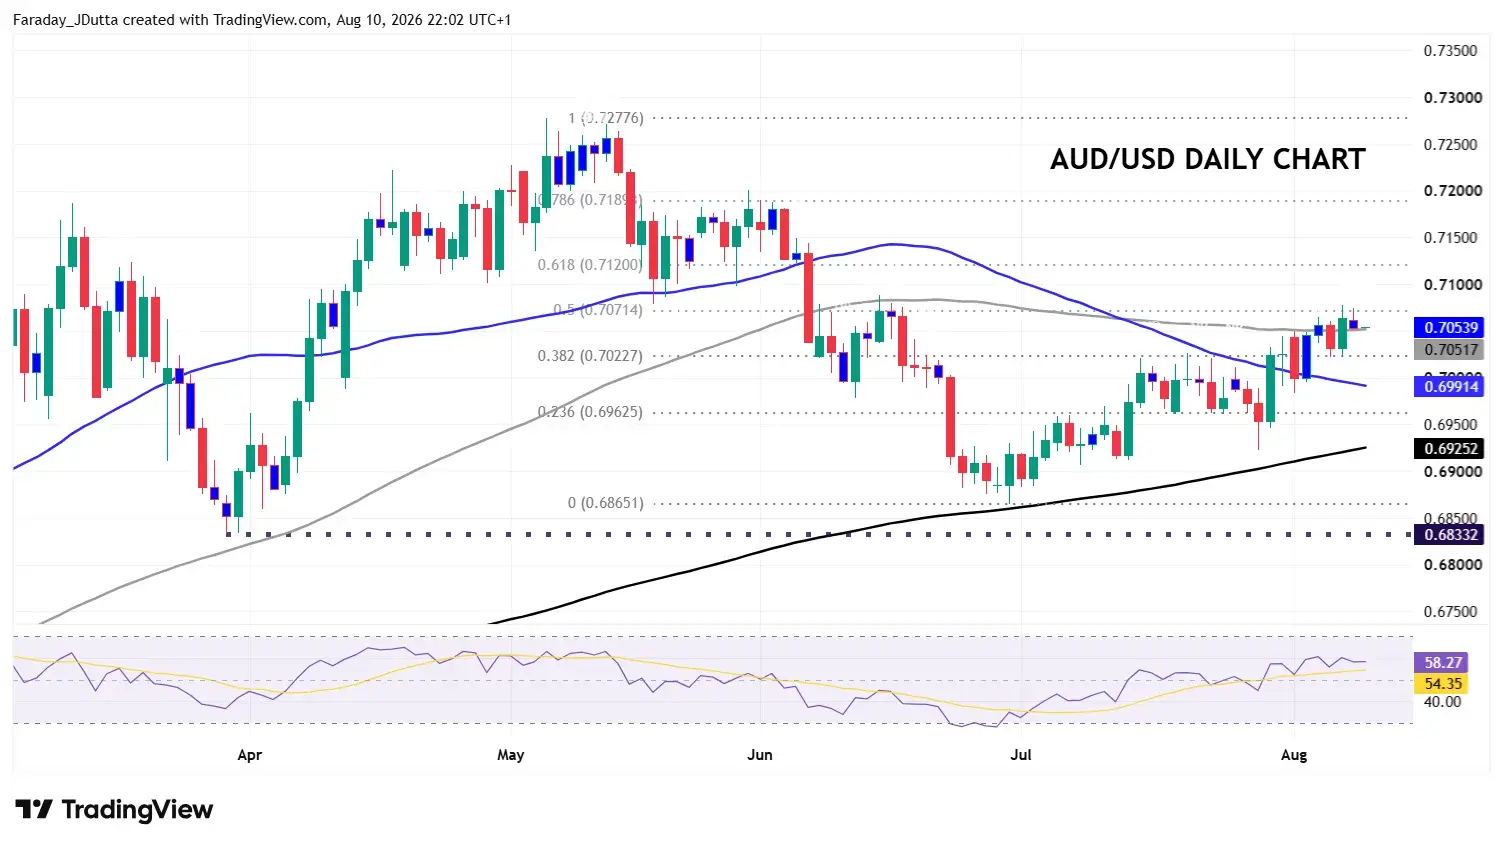
Consensus seems to predict a ‘hawkish hold’ from the RBA. Policymakers likely still want to assess incoming data, essentially using the room created by earlier hikes to see how the economy is faring. For AUD, prices have been rising since the low in June nearly touched the 200-day SMA, not at 0.6922 and this year’s low made in late March at 0.6833. The major is now trading just below the midpoint of the May to June move at 0.7071. The next major Fib level (61.8%) sits at 0.7120, with the 38.2% at 0.6962. A less hawkish RBA could see support at the Fib at 0.7022, with the 50-day SMA below at 0.6991.