Tech drags as rising bond yields cause wider concerns
Jamie Dutta >
Jamie Dutta >
Jamie Dutta is a Market Analyst for Vantage. He comes with extensive experience as a full-time trader and financial market commentator, having worked as a trader in top tier investment banks and trading houses.
 Updated Wed, 2026 August 19 04:31

- Trump says no talks taking place or scheduled with Iran
- Global bond slump sends long-term borrowing costs to highest in decades
- GBP trades lower against USD after soft UK employment data
- Bitcoin pauses at $64,000 as rising yields, oil drag equities lower
Forex
USD was relatively quiet as FX volatility assumed its summer lull, even as Treasury yields and crude oil prices picked up. The global bond market sell-off is getting more attention as borrowing costs edge towards their highest in decades. Deteriorating public finances, lack of central bank buying, plus huge corporate bond supply to fund AI has combined to grab the headlines. The ending of the US-Iran MOU and potentially a ‘never-ending’ war would typically support the dollar. Bets on a September rate hike ticked up to around 36% from 30% at the start of the week. FOMC minutes are released today.
EUR printed a tiny doji candle in keeping with a quiet FX session. Natural gas prices are close to their 2026 highs, and rising crude prices might ordinarily hinder euro upside. But ECB rate hike expectations have also firmed up with 23bps priced for the 10th September ECB meeting, 43bps by year-end and 62bps in total by July next year. Germany’s August ZEW survey reflected better-than-expected sentiment, with Expectations rising to 34, above the forecast of 30 and July’s 26.3. Expectations and (soft but improved) Current Situation data suggest the economy remains in slow recovery mode.
GBP was modestly lower on the day after the first data release of the week saw ongoing softness in hiring and wage growth. The job market still looks relatively cool, which points to a high bar for rate hikes, with markets currently still pricing in 30bps by December and 60bps by July 2027. That said, there’s only a 20% chance of a rate move next month.
JPY continues to trade around the long-term upward trendline around 159.45. But as we said, any mild dips are being bought at present as market test Tokyo’s intervention strategy and continues to put on yen shorts. Japan CPI on Friday is important for the BoJ ahead of its meeting next month. A rate hike is highly likely at that meeting, according to money market bets, with another 25bps move by January next year.
Stocks
US stocks: The S&P 500 lost 0.66% to close at 7,694. The Nasdaq closed down 1.68% at 29,491. The Dow Jones settled lower by 0.22% at 5`3,344. Energy, Healthcare, Consumer Staples and Financials were positive while Technology and Industrials led the laggards. The semiconductor index SOXX slid 5%. Sandisk sunk 9%, Micron fell 7% and Coreweave tumbled 12% as the chip and AI sectors got hit on worries over higher bond yields. In simple terms, these reduce the present value of profits expected years into the future and raise corporate borrowing costs. That is a potential problem for these firms who have enjoyed huge gains on expectations that AI infrastructure spending will keep accelerating. Home Depot closed marginally lower as it beat Wall Street expectations on both sales and profits, offering a mild bright spot for most of the day, despite an otherwise stagnant housing market. See below for Meta.
Asian Stocks: Futures are mixed. APAC stocks were mostly lower on the weak Wall Street lead amid geopolitical uncertainty. The ASX 200 edged higher with earnings helping offset softness in financials and telecoms. The Nikkei 225 slid below 68,000 amid rising yields, fears of BoJ policy tightening and higher energy prices. The Hang Seng and Shanghai Comp were muted following the recent disappointing economic data. Industrial production and retail sales missed forecasts, although the downside in the mainland was cushioned by government measures to boost consumption.
Gold gave back Monday’s gains as Treasury yields rose, even though the greenback was largely unmoved. Markets will look to the release of the Fed’s latest meeting minutes for further direction, while developments in the Middle East remain a key upside risk for prices.
Day Ahead – UK CPI, FOMC Minutes
The UK inflation headline and core prints are seen rising to 2.9% from 2.6% and 2.5% from 2.6%, respectively. The former is due to the 13.5% utility price cap adjustment, which adds roughly 0.4% to the headline. The all-important services inflation is expected to ease two-tenths further to 3.4%, in line with the BoE forecast. July PMIs pointed to a cooling in price pressures, given the lower energy prices seen in the first half of the period. For the BoE, focus remains on the balancing act among the hawks and doves, and ultimately if second round effects are present amid an uncertain economic outlook. In this environment, we expect the BoE to sit on its hands for a prolonged period.
The Fed Minutes will be watched after the confused messaging from new Fed Chair Kevin Warsh at the press conference. We will hear whether there is any shift in thinking within the broader Fed after the June summary of economic projections showed a 9-9 forecast split on whether they predicted a rate hike this year. The minutes could appear a little stale too, with recent soft data in the form of last week’s CPI and the start of the month lower than expected non-farm payrolls report.
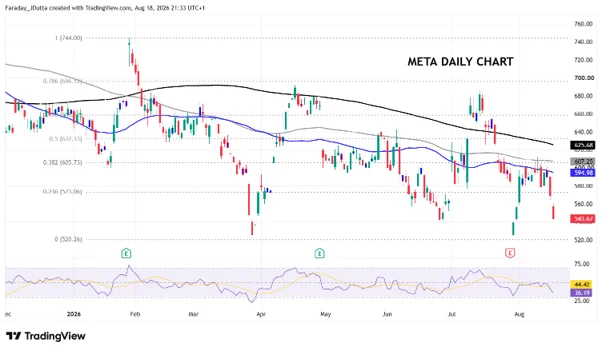
Chart of the Day – Meta sinking to long-term support
Mark Zuckerberg’s Meta has seen strong selling this week, chiefly due to the social media giant facing a 29-state US trial that could reshape Instagram and Facebook. The states allege that Meta intentionally designed those two apps to encourage addictive behaviour in minors, while improperly collecting and using personal data of children. Investors are concerned about potentially steep penalties and structural remedies that could weaken platform engagement.
Technically, apart from its spike high after the January earnings report, prices have been stuck in a range for most of this year between, give or take, $700 and 520. The stock bounced at the end of July after its most recent earnings back to the first major Fib level (38.2%) of this year’s high to low at $605.73. This capped the upside and we are nearing very strong support again around $520.