Tech pushes S&P 500 to record as Treasury yields pressured by soft PPI
Jamie Dutta >
Jamie Dutta >
Jamie Dutta is a Market Analyst for Vantage. He comes with extensive experience as a full-time trader and financial market commentator, having worked as a trader in top tier investment banks and trading houses.
 Updated Fri, 2026 August 14 05:13
- US sends fresh aircraft carrier to Middle East amid Iran war strain
- Canada say US keen on trade deal before August 19 deadline
- *Dollar quiet on flat PPI prices data, cooling Fed rate hike bets
- Anthropic CFO leading early IPO meetings has not discussed valuations
Forex
USD printed a doji candle as a spike high at the start of the European session to two-week highs at 100.08 retraced through the day. A softer-than-expected PPI release saw bets on a Fed hold over a hike increase. There’s now just a one in three chance of a rate hike in September; this was 50:50 pre-US CPI. However, the greenback held up despite the move lower yields, helped by the elevated geopolitical risk environment. Fed speak saw Hammack post PPI reiterate calls for rate hikes whilst Barkin remains uncertain on the future path of policy.
EUR found a small bid as prices remained above 1.15. Yield spreads are still supportive while data releases have been limited to second tier in line industrial production. Any renewed escalation in the Persian Gulf could provide fresh support to the dollar and push the euro closer to the 50-day SMA at 1.1463.
GBP lost ground for a third straight day as cable dipped below 1.35. The preliminary Q2 GDP release was in line with expectations at 0.4% q/q, while showing a better composition with unexpected weakness in government spending offset by minor surprises in consumption and business investment. Money market pricing for the BoE was relatively unmoved with just over a quarter point of hikes priced in by year-end.
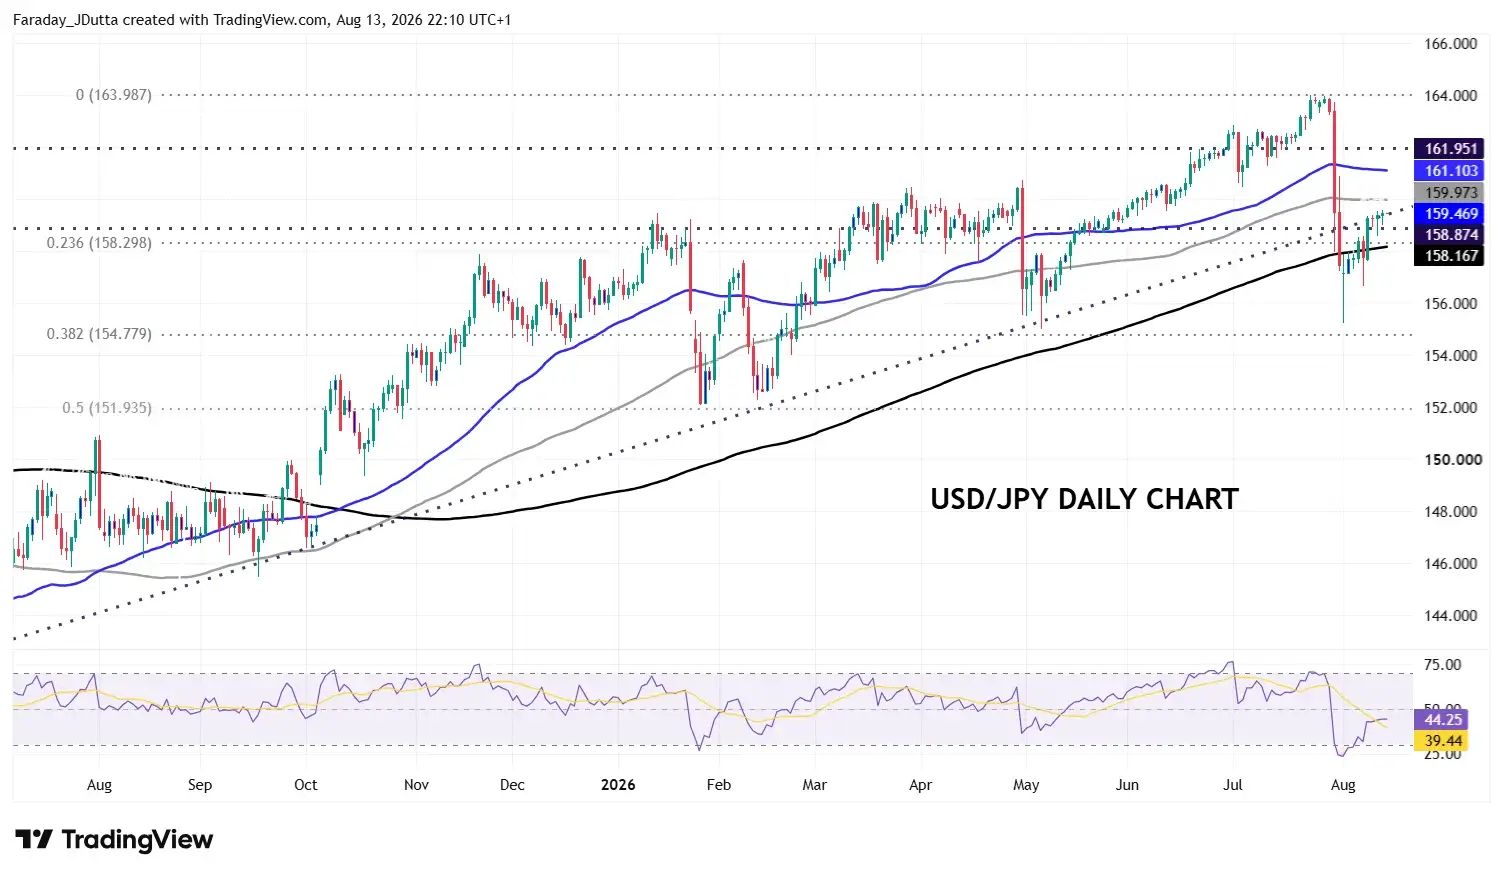
JPY weakened for a second day as the major moved above the long-term upward trendline from the April 2025 low around 159.30. See below for more on the major.
Stocks
US stocks: The S&P 500 added 0.65% to close at 7,799, a record high. The Nasdaq closed up 1.15% at 30,084. The record top from early June is 30,762. The Dow Jones settled higher by 0.13% at 5`3,845. All sectors were green with Communication Services, Real Estate tech and Consumer Staples leading the gainers. Materials was the only sector lower on the day, with Energy, Health and Industrials all flat. Software gains extended in response to reports that Silver Lake is in talks to buy Workday. Meanwhile, Dell and HP were firmer after China’s Lenovo beat Q1 revenue estimates. Coherent fell despite a quarterly beat and strong outlook, as elevated investor expectations for optical networking suppliers limited the upside. Cisco sunk 8.4% as its numbers beat and it issued stronger than expected guidance, but this had been front run already into these earnings.
Asian Stocks: Futures are mixed. APAC stocks were mostly green after the solid Wall Street handover. The ASX 200 was marginally lower amid various earnings releases. The Nikkei 225 rallied amid tech momentum. The Hang Seng and Shanghai Comp diverged with Hong Kong soft after mixed Ten Cent results.
Gold saw a fresh 9-week cycle top before prices moved lower on the day. Treasury yields slid initially before retracing mildly to end off their lows.
Day Ahead – US Retail Sales
Consensus expects the headline and ex autos to print at 0.2% and the control group at 0.3%. The latter metric maps GDP well as it feeds directly into estimates of household consumption. Higher gasoline prices likely weighed on consumer demand and saw weaker vehicles sales. Lower crude prices also likely pulled down sales. Overall, it could be a softer report as that fits in with slower payroll income growth and points to the consumer entering the third quarter with less momentum than the headline GDP figures imply.
Chart of the Day – USD/JPY rising
Bloomberg reported that PM Takaichi’s government is supportive of a near-term rate hike by the BoJ with the next move likely either in September (75% discounted) or October (fully discounted). Pressure on the central bank has been building to give the yen more interest rate backing, following first joint US-Japan FX interventions at the end of July since 1998. This is conundrum facing us and trading the major – pressure from the US for it to go lower but yen shorts loading off challenging Tokyo.
Prices have rebounded from the spike low from early in the month at 155.22. They didn’t quite get to the long-term Fib level at 154.77. Buyers moved the major above the 200-day SMA at 158.14 and have traded around and now above the long-term upward trendline from the April 2025 low, plus the swing high from early 2025. Above here is the 100-day SMA at 159.95 with the 50-day above at 161.10.