Record high stocks as AI bounce continues amid Hormuz optimism
Jamie Dutta >
Jamie Dutta >
Jamie Dutta is a Market Analyst for Vantage. He comes with extensive experience as a full-time trader and financial market commentator, having worked as a trader in top tier investment banks and trading houses.
 Updated Wed, 2026 August 5 04:55

* Iran signals positive Oman talks on Hormuz; considers allowing Europe to clear mines
* Treasury yields slide as oil falls on Treasury Secretary Bessent comments
* Palantir soars 29.5% on ‘otherworldly’ commercial revenue, improved forecast
* SpaceX drops 5.5% after hours even as its posts 92% revenue rise in debut earnings report
FX: USD dipped as prices traded just above the 100-day SMA at 99.72. Near-term hawkish Fed rate hike bets were pared back on more optimism over the Middle East. Treasury Secretary Bessent teased that a Hormuz peace deal might come this week. There are now roughly 32bps priced in for 2026, with roughly a 56% chance of rate hike next month. The latest labour data showed JOLTS job vacancies falling more than expected in June, with the quits rate unchanged and the vacancy rate moving slightly lower – no real market mover.
EUR consolidated recent gains and stayed above 1.15. There were no major eurozone data reports with prices being driven by the broader move in the dollar. The 100-day SMA sits above at 1.1567 with the 200-day at 1.1627. Reports suggest some net inflows into Eurozone bonds as global investors reduce exposure to US Treasury debt. But the euro likely needs rate differentials to move in its favour to lift prices significantly higher.
GBP was similar to the euro in price action with cable tracking marginally higher on the day as it traded just below recent highs. Again, there is limited UK data and news so the broader tone is moving FX. EUR/GBP has steadied after rebounding from multi-month lows around 0.8460 to trade just below the 50-day SMA at 0.8586.
JPY underperformed, which is no surprise after such huge moves in recent days. The major trades just below the 200-day SMA at 157.95, with Monday’s spike low at 155.22 and subsequent rejection of lower prices potentially significant going forward. Is this round of intervention over? That was a major source of downside risk for the major and the dollar, with now a more balanced positioning picture too. Longer-term, prolonged downside likely needs a more dovish Fed and Treasury yields materially lower. All that said, Treasury Secretary Bessent largely reiterated his positive view of the currency and would do whatever it takes to support Japan.
US stocks: The S&P 500 added 1.79% to close at 7,737, a record high, the Nasdaq closed up 3.32% at 29,733 and the Dow Jones settled higher by 1.71% at 5`4,091, a fresh all-time high. The gains were broad-based, with the equal-weight S&P 500 advancing 1.4%, highlighting healthy underlying breadth. Most sectors closed higher led by Technology which surged 4.1%, while Materials and Industrials also strongly outperformed. Both sectors benefited from renewed strength in the AI trade, while Industrials also received support from strong Caterpillar earnings (5.5%) who raised their sales outlook after a strong Q2. Energy was the clear laggard as crude prices tumbled over 5%. Consumer Discretionary, Health Care, Energy and Utilities were the only other sectors to finish modestly lower, reflecting some rotation out of defensive areas. Software saw a strong gains of 4.7%, helped by strong Palantir earnings and guidance which saw the stock soar more than 29%.
Asian Stocks: Futures are green. APAC stocks were mixed with no positive follow through after the record close in the Dow and strong stock performance Stateside. The ASX 200 outperformed with tech and financials strong. The Nikkei 225 took back early gains with a lack of bullish drivers. The Hang Seng and Shanghai Comp were mixed with Hong Kong failing to benefit from strong HSBC earnings.
Gold continued to trade in a range above $4,000. Falling Treasury yields typically boost the appeal of non-yielding precious metals. As we have said for some time, the longer prices track sideways, the bigger the range expansion and breakout typically will be.
Day Ahead – US ISM Services
Non-manufacturing services activity is forecast to rise to 54.3 from 54.0. Prices paid are predicted to ease to 65.0 from 67.7 suggesting inflationary pressures are cooling. This is probably the key component following the volatility in energy prices. Focus is on whether inflationary pressures are spreading beyond goods and transport. Continued expansion in new orders should keep employment above 50. All in, the data should be consistent with another month of reasonable growth.
This report comes after the ISM manufacturing release on Monday, which reached its highest level in four years, reinforcing the improving trend seen recently. It also confirmed the strength already signalled by the regional Fed surveys, led by the very strong Philly Fed release. The underlying components were all equally constructive and confirmed that US cyclical data is still running very solid.
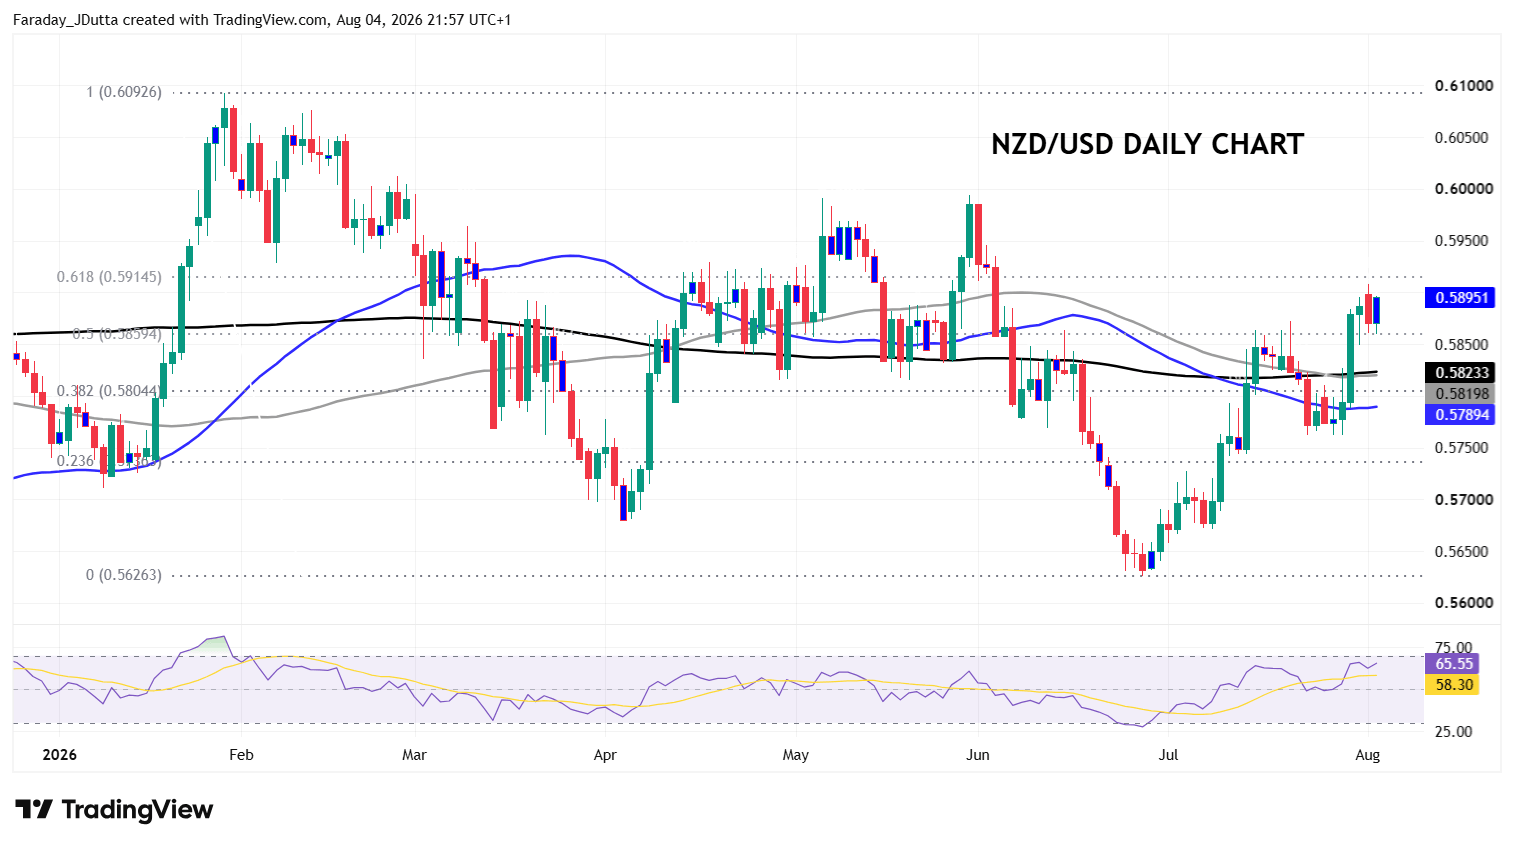
Chart of the Day – NZD in bullish consolidation mode?
New Zealand releases its Q2 jobs data first thing today. High-frequency indicators point to only 0.1% quaterly employment growth, while the jobless rate is forecast to tick up one-tenth to 5.4%. That would broadly match the Reserve Bank of New Zealand’s May projections, which implied one to two hikes in the third quarter. Since July’s hike, markets have continued to virtually fully price in another move at the early September meeting, with two more rises by February. The major broke to the upside above long-term SMAs around 0.5814/23 last Thursday (yen intervention day). The midpoint of the January high to late June low is 0.5859. The major Fib (61.8%) retracement above is 0.5914.