Fed on hold in split vote; Stocks and Dollar dump
Jamie Dutta >
Jamie Dutta >
Jamie Dutta is a Market Analyst for Vantage. He comes with extensive experience as a full-time trader and financial market commentator, having worked as a trader in top tier investment banks and trading houses.
 Updated Thu, 2026 July 30 04:34
* US to strike Iran hard as war escalates again; oil jumps
* Dollar slipped as the Fed held rates steady, but with three hikes dissenters
* Microsoft bounces after revenue beat on cloud strength, capex in line
* Meta fell after it bumped up capex outlook amid AI spending worries
FX: USD sold off with its worst day since the start of the month, after the Fed decision to leave rates unchanged. There had been around a 37% chance of a rate hike, before the meeting. The outcome was viewed as a ‘hawkish hold’ with three officials voting for a rate hike, one more than consensus predicted, with inflation described in the statement as remaining elevated. The press conference also saw more modest selling in the greenback as hawkish rate expectations were pared back. Money markets now see a 36% chance of a September hold, versus 24% when the day started. Warsh actually doubled down on his pledge to tackle inflation and hailed ‘commonality’ among policymakers. Heightened Middle East tensions saw Brent jump 7.9% as it bounced off its 200-day SMA, now at $80.25.
EUR climbed after the hold decision by the Fed as prices rose up above the downward trendline from the May highs. ECB rate expectations are steady meaning ongoing support via interest rate differentials. If broader Middle east de-escalation and some possible Fed dovish re-pricing take hold, then prices could move up to the 50-day SMA at 1.1485 and beyond.
GBP rose with the 50-day SMA in cable at 1.3353. As we said yesterday, BoE rate expectations like EUR ones are showing signs of stabilisation and offering some modest support to the pound. Focus moves to today’s BoE meeting and new quarterly economic projections. See more below.
JPY strengthened but still sits not far off long-term highs just below 164. Attention is shifting to this week’s BoJ meeting. There is the potential for domestically-driven strength if policymakers deliver a hawkish hold and seek to build on the 25bps of tightening by December currently priced into the short-term rates market.
AUD was the major underperformer as Australian inflation came in softer than expected. Headline CPI slowed from 4.0% to 3.8% in June, while the trimmed mean – the RBA’s preferred core measure – held at 3.6% against expectations of 3.7%. Markets sharply pared back RBA tightening expectations, from around 20bp before the release to 13bp. This move be excessive as higher energy prices in July suggest inflation data over the rest of the summer could prove less reassuring. Also, Governor Michele Bullock has continued to signal that additional tightening might still be required to return inflation to target.
US stocks: The S&P 500 lost 1.52% to close at 7,316, the Nasdaq closed down 2.06% at 27,192 and the Dow Jones settled lower by 2.19% at 5`1,599. Only two sectors were in the green, Energy and Consumer Staples. Industrials and Tech were the biggest laggards. The SOXX chip index fell again, closed on its lows and has declined over 28% since its record high in June. Seagate closed higher by 7.5% after blowout earnings fuelled by AI demand were released after Tuesday’s close. But chip stock leaders like Nvidia and Micron fell with the latter off 9.9%. The former is trading on its 200-day SMA at $193.01. Alphabet outperformed up 0.9% and has risen around 8% since its lows after its earnings report and capex plans released last week. Meta closed down 6.4% after hours as it posted falling profits and weak sales. Microsoft was 3.4% higher after it announced strong earnings, Azure cloud sales surpassing $100 billion and inline capex.
Asian Stocks: Futures are mixed. APAC stocks were choppy with initial tech gains being erased through the day. The ASX 200 outperformed with defensives in the green as Rio Tinto results and cooler inflation, which saw RBA rate hikes bets pared back. The Nikkei 225 rallied early on before giving back gains. The Kospi suffered another eye-opening session, with stocks initially buoyed following mixed results from SK Hynix, which beat on Q2 net but missed on operating profit and revenue. That saw the index then slump which eventually triggered circuit breakers. The Hang Seng and Shanghai Comp were mixed, with the former driven by Chinese automakers/EV names, while the mainland was muted amid ongoing trade-related frictions.
Gold got a boost from the on hold Fed rate decision as bets on a hike were pared back for September. The falling trendline from the record highs comes in around $4141, with the 50-day SMA at $4217.
Day Ahead – BoE Meeting
The MPC will sit on their hands and keep rates steady at 3.75%. On hold for the foreseeable future seems to be the playbook with a relatively robust economy and inflation still sticky above target lending it a mildly hawkish bias. However, the uncertainty around the Middle East situation, US tariffs, domestic political uncertainty and relative policy space means ‘steady as she goes’ remains the base case, as the trade-off Governor Bailey described in June continues.
Focus will be on the vote split which may be more hawkish than the 7-2 we saw last time, with activist Mann the most likely contender to also vote for a hike. A fresh MPR will be watched for any hawkish signal given the energy price re-acceleration. Overall, the MPC majority will likely continue to wait for more clarity on the geopolitical situation and data on the energy impact of the shock before a potential rate rise. Markets are pricing in two 25bps by March next year. There is currently less than a 5% implied chance of a July hike.
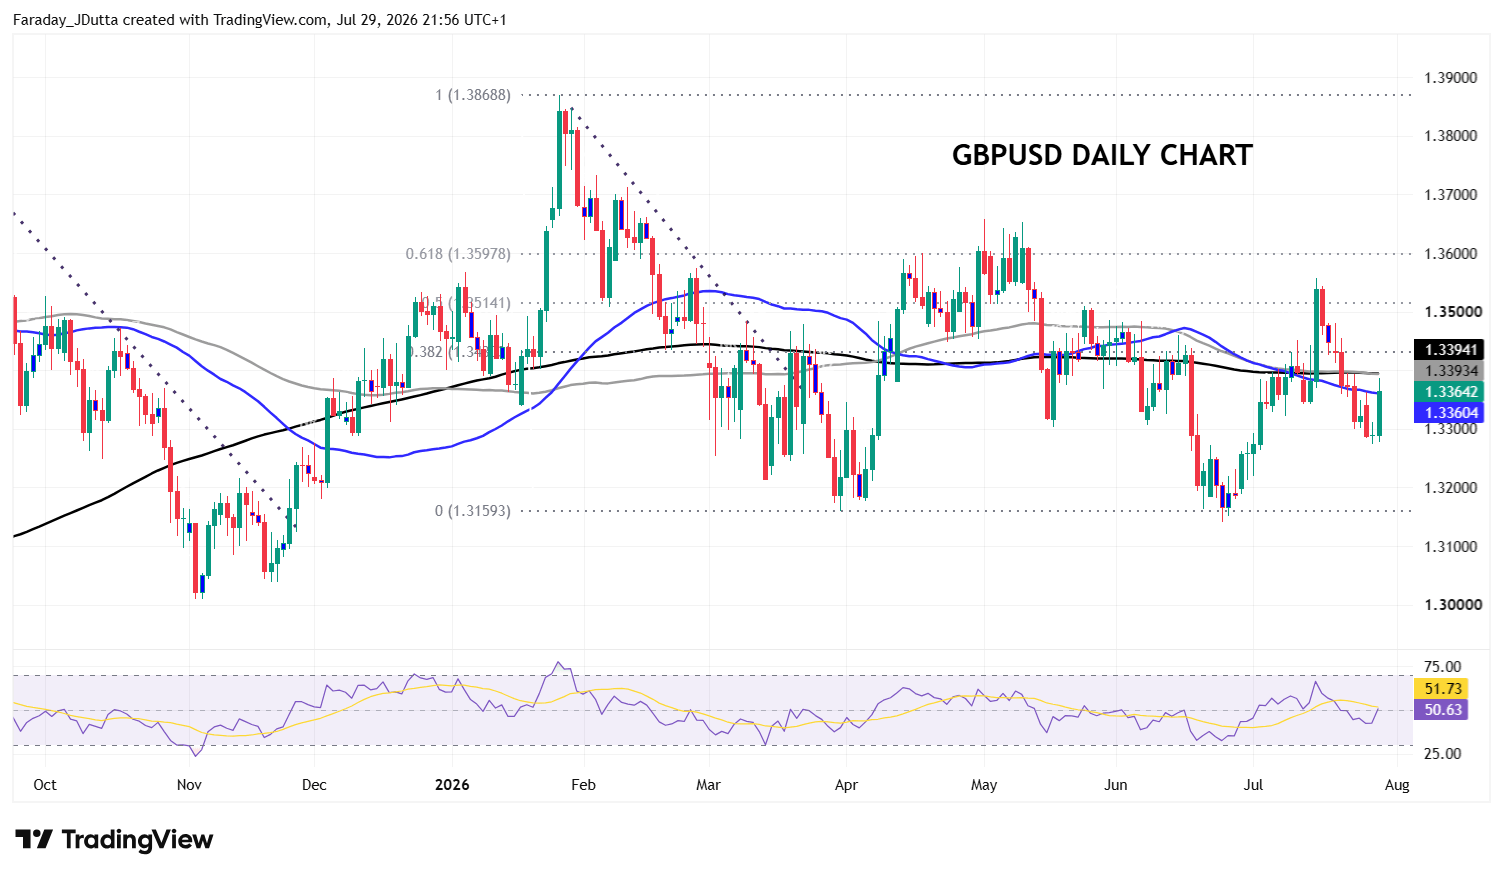
Chart of the Day – Cable mid-range waiting for catalyst
GBP/USD picked up due to dollar selling after the Fed. Markets were relieved with Chair Warsh’s comments and the more patient stance than predicted. On the other side, eyes are of course on the today’s BoE. UK domestic political developments have been limited as UK media continue to focus on PM Burnham’s fiscally-motivated plans for welfare reform. The narrative is important as the UK remains vulnerable to volatility in its government debt market.
The daily RSI had been showing signs of stabilisation in the lower 40s, implying modest bearish momentum below the neutral threshold at 50. The Fed decision has seen the dollar soften and the RSI pick up towards that midpoint. The local range from June is bound between support near 1.3150 and resistance closer to 1.3550. Indicators are all relatively neutral truth be told, unless there’s a break of the range. The 50-day SMA sits just above at 1.3360 and the 200-day above here at 1.3394.