Yields jump, stock slide after Bessent intervention fails
Jamie Dutta >
Jamie Dutta >
Jamie Dutta is a Market Analyst for Vantage. He comes with extensive experience as a full-time trader and financial market commentator, having worked as a trader in top tier investment banks and trading houses.
 Updated Fri, 2026 August 21 05:17
- Bessent says Treasury buyback operation could be more than $4bn
- Investors warn US over shifting from predictable debt management
- US unlikely to restart large scale Iran combat amid stalled talks
- Anthropic expects to match SpaceX’s record IPO size or top it
Forex
USD clawed back losses after prices initially dipped to fresh three-month lows at 98.55. Markets are still digesting the action and implications of Wednesday’s US Treasury attempt to calm bond markets. ‘Big Brother Bessent’, the ‘Bessent put’ and ‘Bessent bail-out’ are just a couple of headlines we have read. He and the administration are trying to manage longer-term rates, which have been rising because markets are questioning the Fed’s commitment to inflation fighting and investors are worried about the sustainability of US fiscal policy. If yields can’t fully take the strain from those concerns, the dollar may have to. That implies that the dollar debasement trade is back. It also potentially reduces one of the key threats to risk assets this summer and could see carry trade strategies remaining popular. Bessent was on the wires trying to further bolster his policies. But judging by yesterday’s price action, this was seen as lacking credibility, meaning this could contribute to higher yields over time should Treasury become more opportunistic in its approach to debt management.
EUR posted a fresh cycle high at 1.1710 in the European session before closing only marginally higher on the day, with a bearish candle rejecting higher prices. Rate differentials have narrowed a lot since the start of July helping support the euro in recent weeks. But that direction changed this week as investors reacted badly to US policy.
GBP rose further as the pound outperformed its peers, with cable hitting a high of 1.3659. It’s really all about the dollar moves at present, with no action expected at the BoE meeting next month. This week’s data has not rocked the boat, though divisions at the MPC are still likely live.
JPY weakened as Treasury yields reversed Wednesday’s move lower. That saw the major rebounding off the 200-day SMA at 158.27. The long-term upward trendline around 159.45 remains long-term support/resistance.
Stocks
US stocks: The S&P 500 lost 0.87% to close at 7,641. The Nasdaq closed down 0.72% at 29,213. The Dow Jones settled lower by 1.32% at 5`2,764. All sectors were lower apart from Energy and Real Estate while Materials were flat. Consumer Staples, Health Care and Consumer Discretionary lagged. Health Care gave back some of Wednesday’s Moderna (-26.6%)/Merck (-2.1%) -induced gains, while Staples were weighed on by Walmart (-9.2%). The world’s largest bricks and mortar retailer tumbled after posting disappointing guidance while quarterly sales fell short of expectations, a rare miss. That stoked concerns about the mega retailer decelerating alongside a slow-growing US economy.
Asian Stocks: Futures are mixed. APAC stocks were mostly higher after the positive lead Stateside. The ASX 200 edged higher on miners amid earnings updates. We had disappointing jobs data in which headline employment change contracted and the jobless rate rose. The Nikkei 225 was helped by a tech rebound and pullback in yields. The Hang Seng and Shanghai Comp were positive but gains were capped as investors waited for Alibaba’s earnings.
Gold
Gold was choppy with initial losses retraced and prices closing very marginally lower but still above the 200-day SMA, which resides at $4,498. If the bar has been set for real yields to fall, plus a softer dollar and concerns about the Treasury fiscal influence over financial conditions, bullion could see further upside.
Day Ahead – Global PMIs
Eurozone business survey activity data is forecast to ease after July’s stronger prints, though it should stay consistent with modest growth. Manufacturing PMI is expected to edge higher to 52.0 in August (previously 51.9), while Services and Composite PMIs previously stood at 51.6 and 51.9. There have been regional differences between Germany and France (Services and Composite in contraction) while we will be watching price gauges and delivery times, which could point to underlying inflationary pressures.
UK PMIs are seen ticking very modestly lower with Manufacturing at 51.5 from 51.9 after two months of decline, Services at 51.8 from 52.1 prior and the Composite at 51.6 and 52.2. The payback in the services PMI follows a material jump in July. UK retail sales are also released with mixed surveys from BRC which disappointed and the CBI which was more upbeat. The headline is seen at -0.5% with the summer heat a hindrance to consumers.
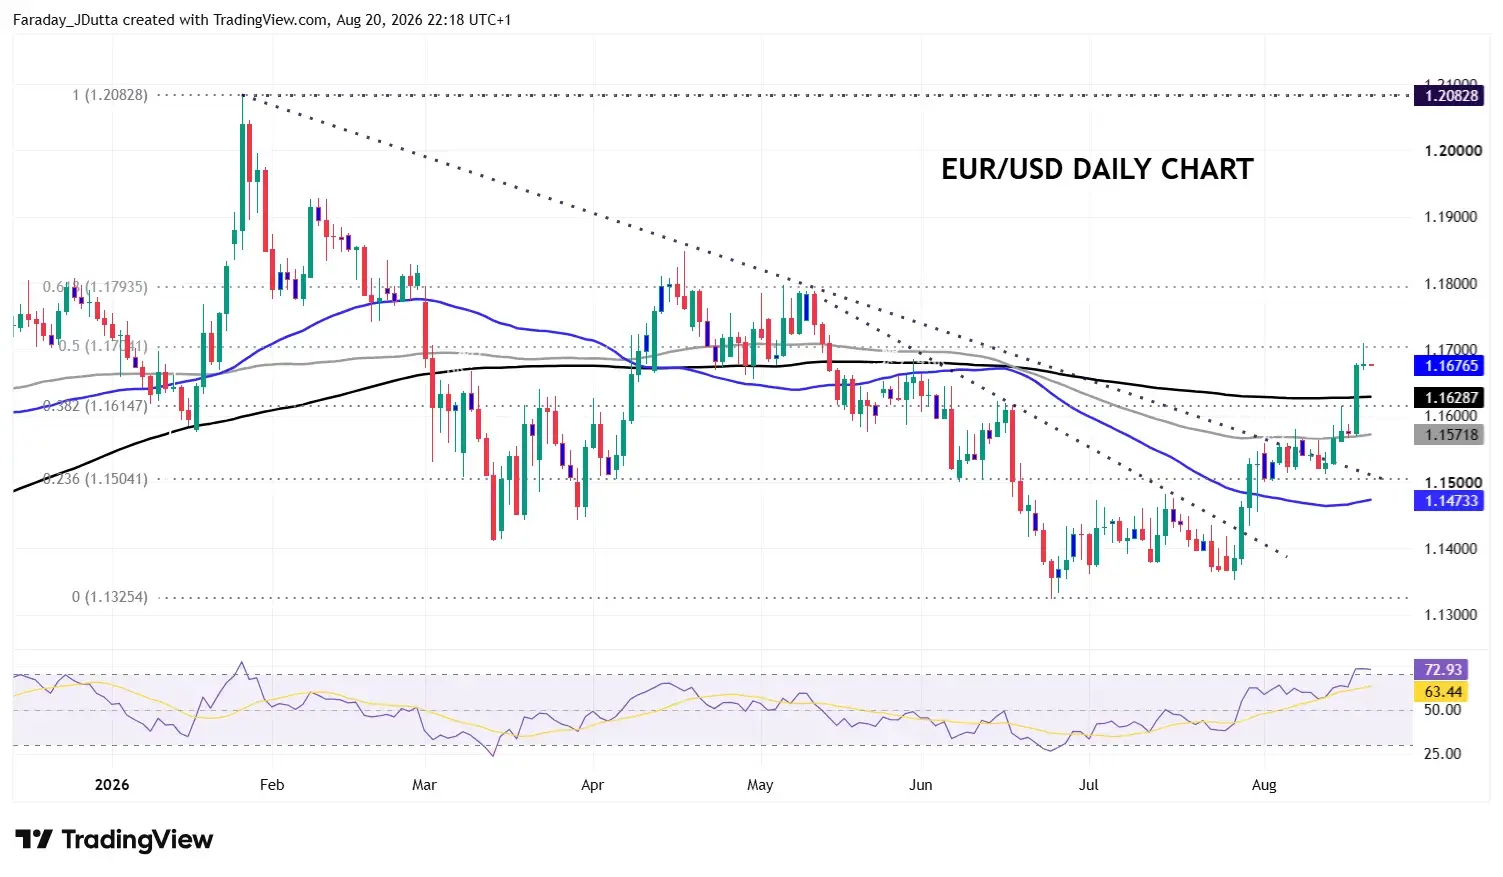
Chart of the Day – EUR/USD overbought & bearish candle?
Since chopping around 1.14 in the early part of the summer, the world’s most popular currency pair pushed up through the 50-day SMA, now at 1.1473. Prices then tracked sideways again just above 1.15, before a break of the long-term downward trendline from the January 2026 top. Thursday’s upside breakout cut through the 200-day SMA at 1.1628 and the major Fib level of the 2026 high to low at 1.1614. But yesterday’s printing of a potentially bearish shooting star candle warns of a rejection of higher prices. It also tapped the midpoint of the 2026 high to low at 1.1704 before reversing gains. Prices are overbought on momentum indicators, but this doesn’t mean we can’t go higher. The 61.8% retracement of the first half decline sits at 1.1793.