Updated
Gold ETFs (exchange-traded funds) entered 2026 at an unusual scale. The World Gold Council’s June 2026 report valued global gold ETFs’ AUM (assets under management) at approximately USD526 billion at the end of June, with collective holdings of 4,047 tonnes.1
That scale does not mean one fund is automatically the best gold ETF for every investor. The largest fund may offer deeper trading and options markets, while a smaller physical-gold trust may charge less each year. A mining fund may distribute income, but it introduces company, operating, and equity-market risks that bullion trusts do not.
This guide is designed to compare 10 of the best gold ETFs and exchange-traded gold trusts available to many investors through US markets. The list covers eight physically backed products and two gold-mining equity funds.
Disclaimer: This article is intended for informational purposes only. It uses issuer information available up to 28 July 2026, but fund assets, spreads, volumes, holdings, and product terms can change. The list is a comparison set, not a ranking or personal recommendation. The most relevant fund depends on the exposure required, expected holding period, trading size, jurisdiction, access, and capacity for loss.
Key Points
• IAUM has the lowest stated sponsor fee in this comparison at 0.09%, while its filings also describe a temporary fee waiver that may reduce the effective fee through 30 June 2027.
• GLD remains the largest physical-gold product in this group and offers listed options, which can matter to institutions and active market participants despite its higher 0.40% expense ratio.
• Physical gold trusts generally do not pay dividends because bullion produces no income, whereas gold-mining ETFs may make distributions when their underlying companies pay dividends.
• Gold-mining ETFs are equity funds rather than clean gold-price trackers because production costs, management, debt, jurisdiction, and wider share-market conditions affect their returns.
What Is a Gold ETF?
A gold exchange-traded fund (ETF) or exchange-traded product seeks to provide gold-related market exposure through securities that trade on an exchange. Investors can buy and sell shares during market hours through a brokerage account. However, the legal and economic exposure depends on what the product owns.
A physically backed gold trust holds bullion through one or more custodians and aims to reflect the gold price after fees and liabilities. Its shares represent an interest in the trust, not a specific retail bar in the investor’s name. Most retail holders cannot exchange an individual share for gold because creation and redemption normally occur through authorised participants in large baskets.
A gold-mining ETF owns shares in mining, royalty, or streaming companies. Its value can respond to gold prices, but company earnings, production costs, reserves, financing, and political conditions also matter. Some other products use futures, derivatives, currency hedges, or leverage; those structures are outside this comparison because they answer a different search intent.
Readers who need a wider introduction to fund mechanics can start with Vantage Markets’ ETF guide for beginners.
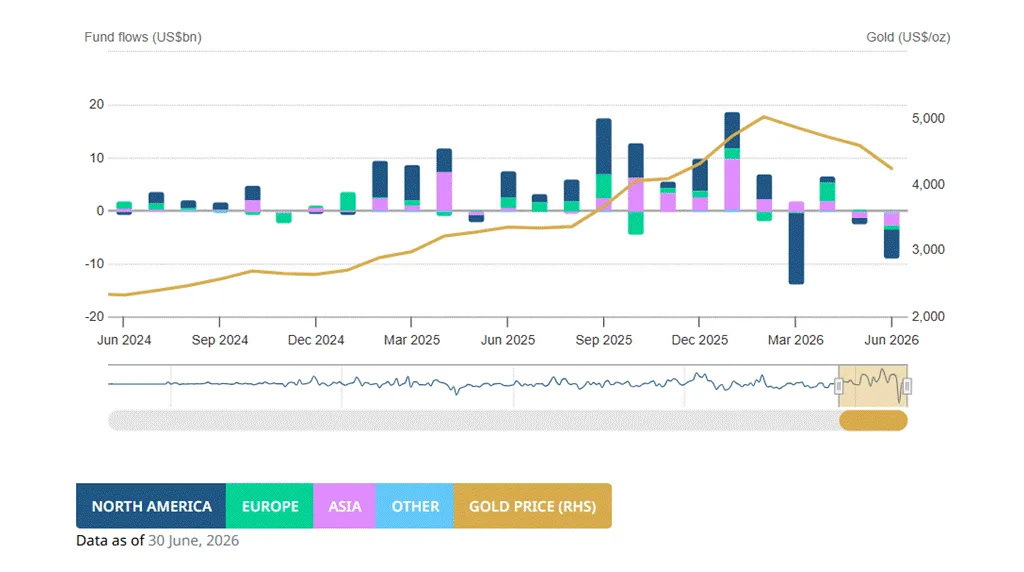
Image credit: World Gold Council
How Were the Best Gold ETFs Selected?
The term ‘best’ can create a false impression of certainty. This comparison therefore uses six observable dimensions rather than a single performance ranking. Recent returns were not used as the main filter because they might encourage investors to chase an already-completed move.
• Fund structure was assessed first because physical bullion and mining shares have materially different return drivers and risks.
• Expense ratios and sponsor fees were compared because recurring charges reduce the amount of gold or portfolio value represented over time.
• Fund size, market activity, spreads where issuers publish them, and options availability were considered as liquidity indicators.
• Custody, bar-list transparency, audit practices, and physical-delivery terms were reviewed for bullion products.
• Distributions were considered because physical trusts and equity funds differ substantially on income.
• Product access and practical use were considered without assuming that a US-listed product is available or tax-efficient in every jurisdiction.
This list includes several low-fee bullion trusts, the largest and most actively followed physical product, a deliverable trust, and two mining funds. Keep reading to find out which are the 10 best gold ETFs that investors and traders might want to keep an eye on in 2026.
10 Best Gold ETFs in 2026: Here’s Our Honest Take
Note: The table provides a dated snapshot, not live dealing data. AUM is rounded from issuer or regulatory disclosures, and the dates vary because providers update on different schedules. Investors should refresh every figure and review the latest prospectus before acting.
| Ticker | Fund | Exposure | Fee | Approx. AUM and Date | Comparison Role |
| GLD | SPDR Gold Shares | Physical gold | 0.40% | USD131.95bn; 24 Jul 2026 | Scale, market depth, and listed options |
| IAU | iShares Gold Trust | Physical gold | 0.25% | USD60.43bn; 24 Jul 2026 | Large fund with lower fee than GLD |
| GLDM | SPDR Gold MiniShares | Physical gold | 0.10% | USD27.64bn; 24 Jul 2026 | Lower-fee SPDR gold exposure |
| IAUM | iShares Gold Trust Micro | Physical gold | 0.09% stated | USD6.38bn; 24 Jul 2026 | Lowest stated fee in this set |
| SGOL | abrdn Physical Gold Shares ETF | Physical gold | 0.17% | USD7.87bn; 31 Mar 2026 | Allocated gold and custody transparency |
| AAAU | Goldman Sachs Physical Gold ETF | Physical gold | 0.18% | USD2.40bn; 30 Jun 2026 | Mid-range physical-gold fee |
| BAR | GraniteShares Gold Trust | Physical gold | 0.1749% | USD1.59bn; 31 Mar 2026 | Low sponsor fee |
| OUNZ | VanEck Merk Gold ETF | Physical gold | 0.25% | USD2.60bn; 22 Jun 2026 | Retail physical-delivery feature, subject to terms |
| GDX | VanEck Gold Miners ETF | Large gold miners | 0.51% | USD21.76bn; 17 Jul 2026 | Diversified major-miner equity exposure |
| GDXJ | VanEck Junior Gold Miners ETF | Junior miners | 0.52% | USD7.05bn; 24 Jul 2026 | Higher-risk smaller-miner exposure |
Physical trusts often report a sponsor fee or trust expense, while registered equity ETFs report gross and net expense ratios. Temporary waivers, extraordinary expenses, trading costs, and tracking differences can alter the realised result.
1. SPDR Gold Shares (GLD)
Best for: Maximum liquidity and institutional-grade trading
SPDR Gold Shares is the largest physical-gold product in this comparison. The official GLD fund page reported AUM of USD131.95 billion on 24 July 2026 and a gross expense ratio of 0.40%. Its objective is to reflect the performance of gold bullion, less expenses, and its gold custodians are HSBC Bank plc and JPMorgan Chase Bank, N.A.2
GLD’s main comparison strength is market infrastructure rather than cost. It has listed options and a long operating history, which can matter to institutions, hedgers, and participants executing larger or more complex trades. Its 0.40% fee is the highest among the eight physical products here, so an investor expecting a long holding period should compare that recurring drag with lower-fee alternatives.
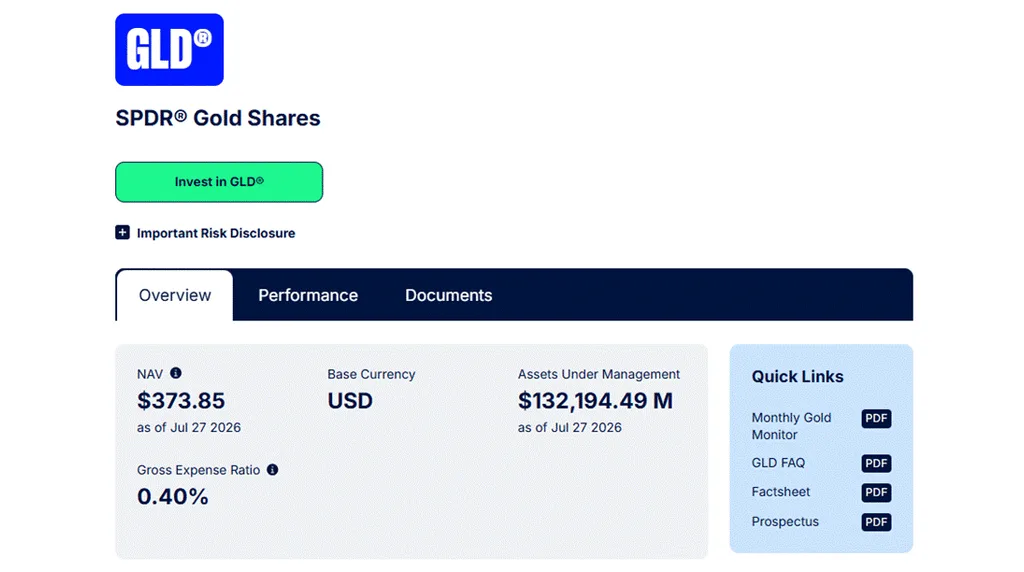
Image credit: State Street Investment Management
2. iShares Gold Trust (IAU)
Created in 2005, the iShares Gold Trust reported net assets of USD60.5 billion, a 0.25% sponsor fee, a 0.01% 30-day median bid–ask spread, and 30-day average volume of approximately 5.10 million shares on 24 July 2026. Its distribution frequency was listed as none.3
In terms of fees, IAU sits between GLD and the micro or mini trusts. Its large asset base and published spread data can make it a useful benchmark for investors who want physical-gold exposure with a lower recurring charge than GLD. Share price, spread, and volume should still be checked at the intended dealing time because historical averages do not guarantee future execution.
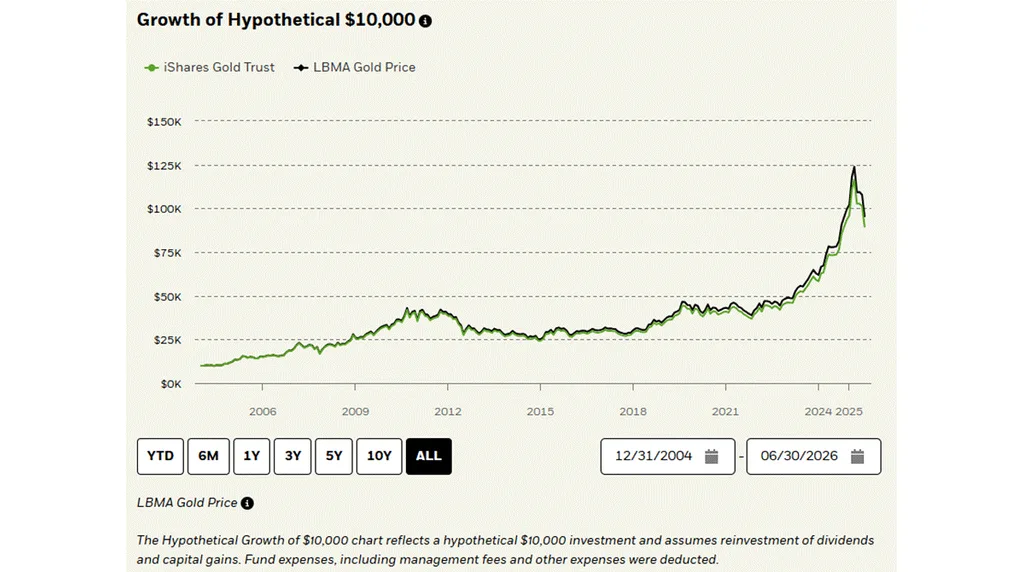
Image credit: iShares.com
3. SPDR Gold MiniShares (GLDM)
The SPDR Gold MiniShares fund page listed a 0.10% gross expense ratio and an AUM of USD27.69 billion as of 27 July 2026. GLDM seeks to reflect the gold bullion price after expenses and uses JPMorgan Chase Bank, N.A. as its gold custodian.4
GLDM provides a lower-fee route within State Street’s gold range. It does not have the same listed-options feature as GLD, so the two products should not be treated as interchangeable for every strategy. For a conventional long-only allocation, the fee difference may receive more weight; for options or very large transactions, GLD’s market ecosystem may matter more.
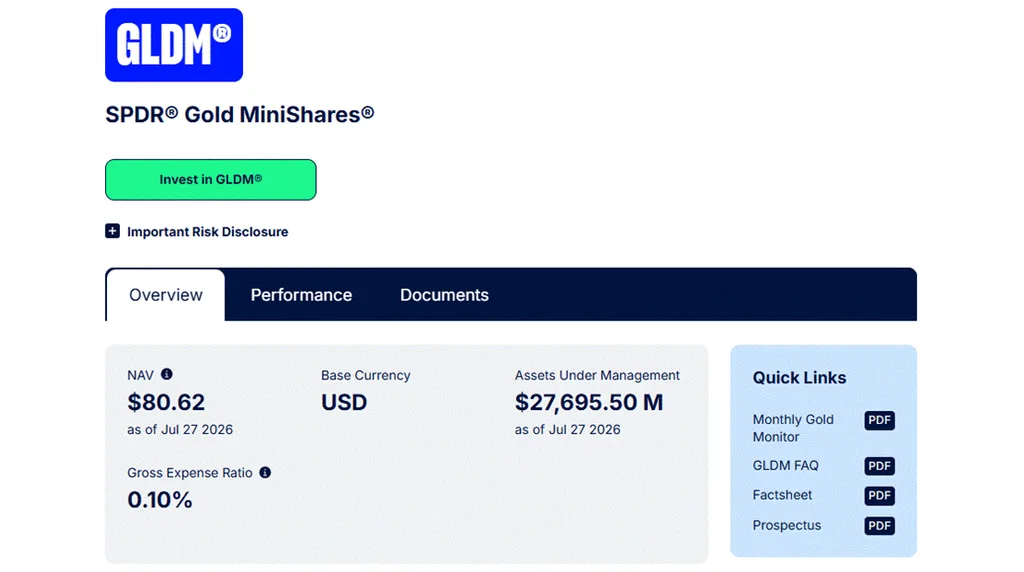
Image credit: State Street Investment Management
4. iShares Gold Trust Micro (IAUM)
The iShares Gold Trust Micro displayed a 0.09% stated sponsor fee, net assets of USD6.38 billion, a 0.02% 30-day median bid-ask spread, and 30-day average volume of approximately 1.80 million shares as of 27 July 2026. Its distribution frequency was none.5
IAUM has the lowest stated sponsor fee in the comparison. Its annual filing describes a voluntary waiver that reduces the sponsor fee to no more than 0.07% through 30 June 2027, although waivers can expire or change under their stated terms.6 Investors should confirm the effective fee in the latest prospectus rather than assuming the reduced rate will continue.
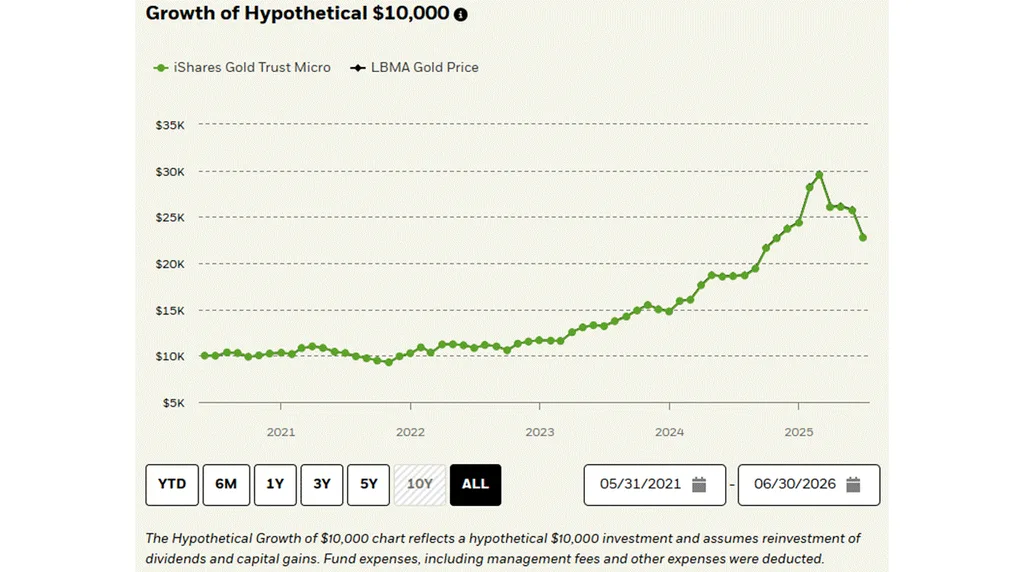
Image credit: iShares.com
5. abrdn Physical Gold Shares ETF (SGOL)
SGOL seeks to reflect the gold bullion price after trust expenses. Its quarterly regulatory filing reported roughly USD7.87 billion of net assets at 31 March 2026, an annualised 0.17% expense ratio, and about 1.71 million ounces of gold. It also stated that all trust gold was held with ICBC Standard Bank Plc at that date.7
SGOL is relevant to investors who place additional weight on custody disclosures, allocated bars, bar-list transparency, and independent vault inspections. Those features do not eliminate gold-price, custody, market, or structural risk. They are due-diligence points to compare with other physical trusts, not evidence that the product is universally superior.
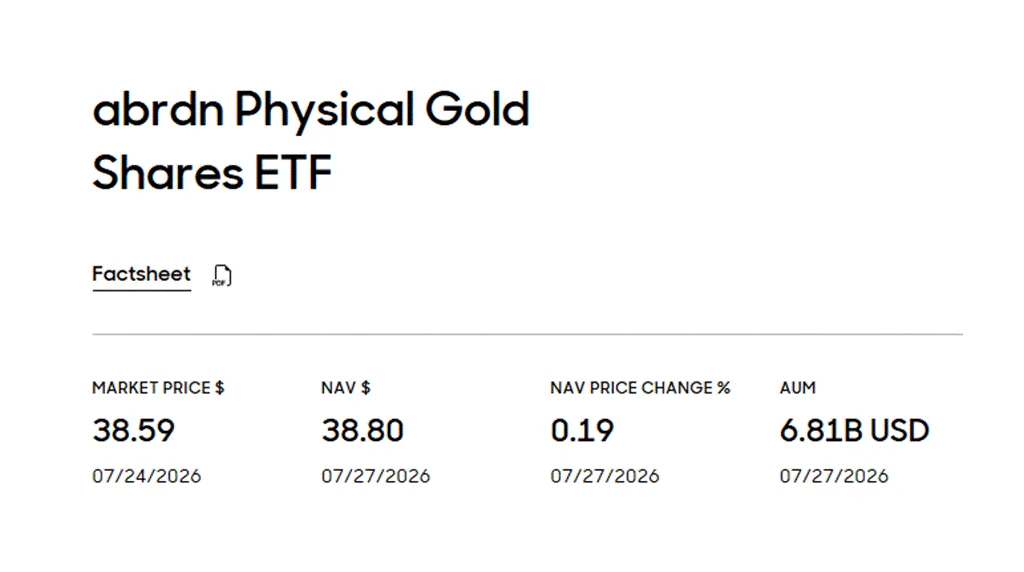
Image credit: Aberdeen Investments
6. Goldman Sachs Physical Gold ETF (AAAU)
The Goldman Sachs Physical Gold ETF fact sheet reported a 0.18% total expense ratio and roughly USD2.40 billion of net assets as of 30 June 2026. Its objective is to reflect the gold price after the trust’s operating expenses.8
AAAU’s fee is close to SGOL and BAR, placing it between the lowest-cost micro products and the larger GLD or IAU trusts. The trust sells or transfers gold to meet fees and expenses, so the gold represented by each share can decline over time. As with other bullion trusts, the investor should review custodian arrangements, bar reporting, prospectus risks, and secondary-market spreads.
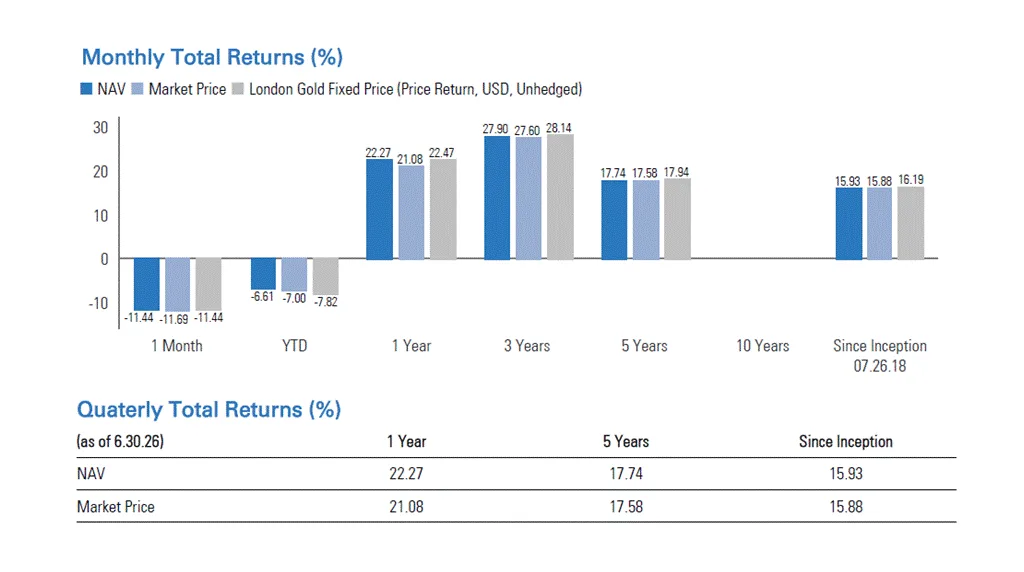
Image credit: Goldman Sachs Asset Management
7. GraniteShares Gold Trust (BAR)
GraniteShares Gold Trust seeks to track the value of its gold holdings after expenses. Its March 2026 quarterly report reported USD1.59 billion of net assets and 345,784.527 ounces of gold. The recurring sponsor fee accrued at an annualised rate of 0.1749% of adjusted daily net asset value.9
BAR’s fee is competitive within the middle of this physical-gold group. However, a difference of only a few basis points may be smaller than the cost of crossing a wider spread or converting currency for a short holding period. The product’s smaller size relative to GLD, IAU, and GLDM makes live liquidity checks particularly important for large orders.
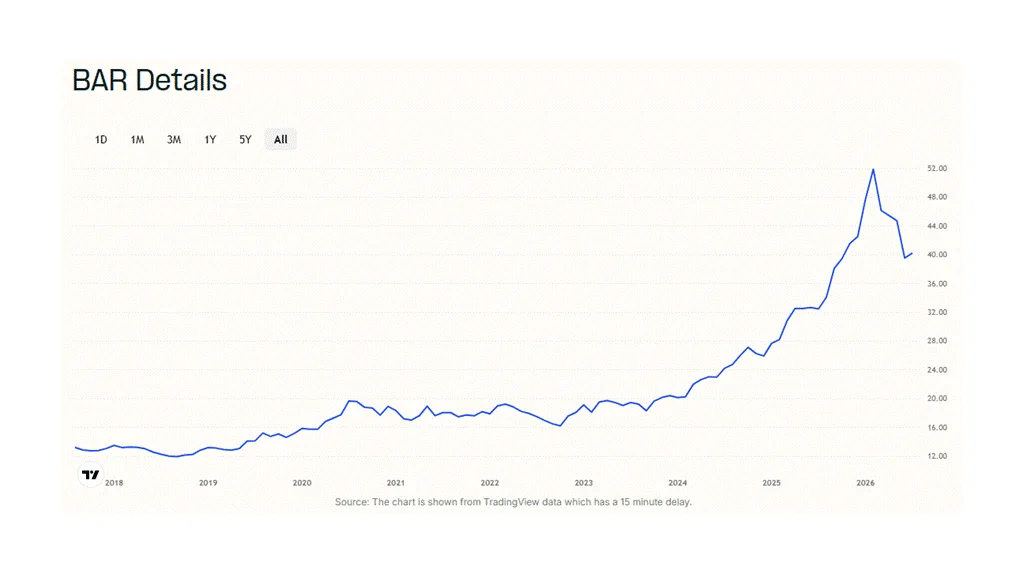
Image credit: Graniteshares
8. VanEck Merk Gold ETF (OUNZ)
The VanEck Merk Gold ETF reported a 0.25% expense ratio and approximately USD2.60 billion of net assets as of 27 June 2026. OUNZ holds allocated London bars and offers a process through which investors may apply to take delivery of physical gold, subject to its procedures, fees, minimums, and eligibility conditions.10
OUNZ therefore answers a different requirement from a conventional low-fee trust. Delivery can be relevant to investors who want a defined route from shares to bullion, but it’s not costless or automatic. Applicants must study the current delivery application, available forms of gold, processing charges, taxes, shipping, insurance, and local restrictions.
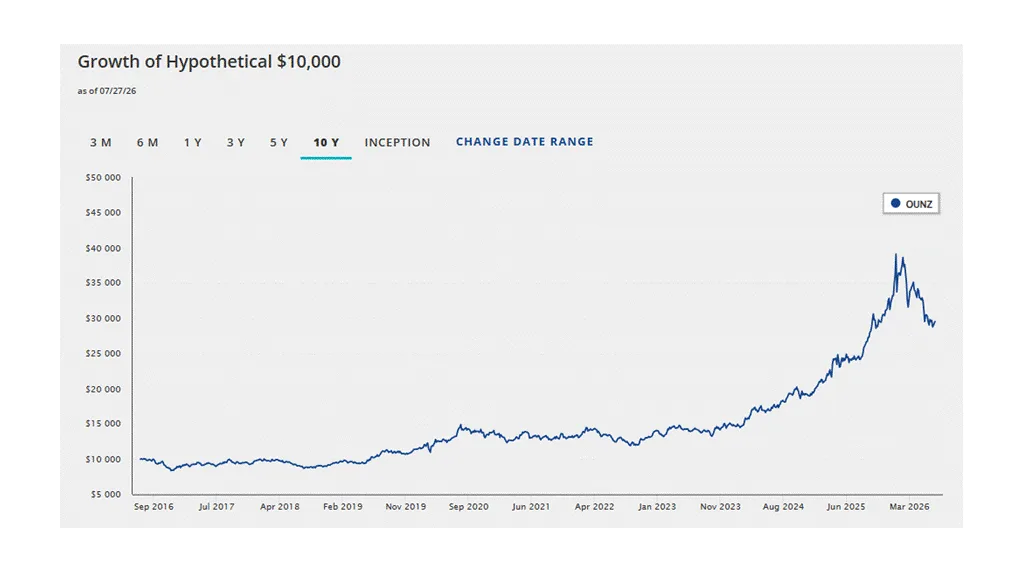
Image credit: VanEck
9. VanEck Gold Miners ETF (GDX)
The VanEck Gold Miners ETF seeks to track an index of companies involved in gold mining. VanEck reported USD23.09 billion of net assets on 27 July 2026 as well as gross and net expense ratios of 0.51%. 11
Gold ETF investors and traders should note that GDX is not a substitute for physical gold. A higher gold price may support miner margins, but diesel, labour, royalties, grades, permitting, taxes, hedging, acquisitions, and management decisions can change the result. Its companies may distribute dividends, which creates an income channel absent from bullion trusts, although distributions and yields are not fixed.
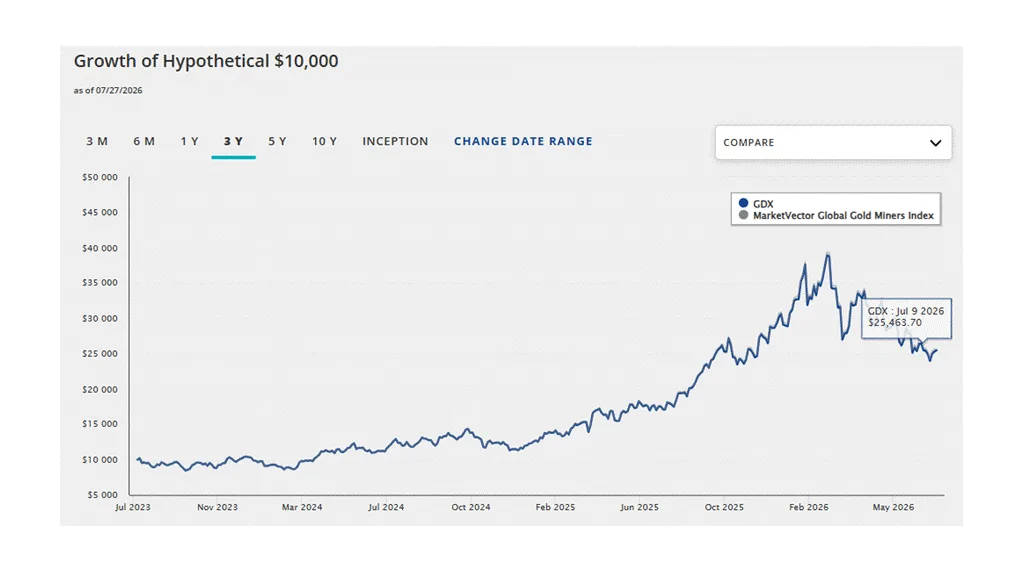
Image credit: VanEck
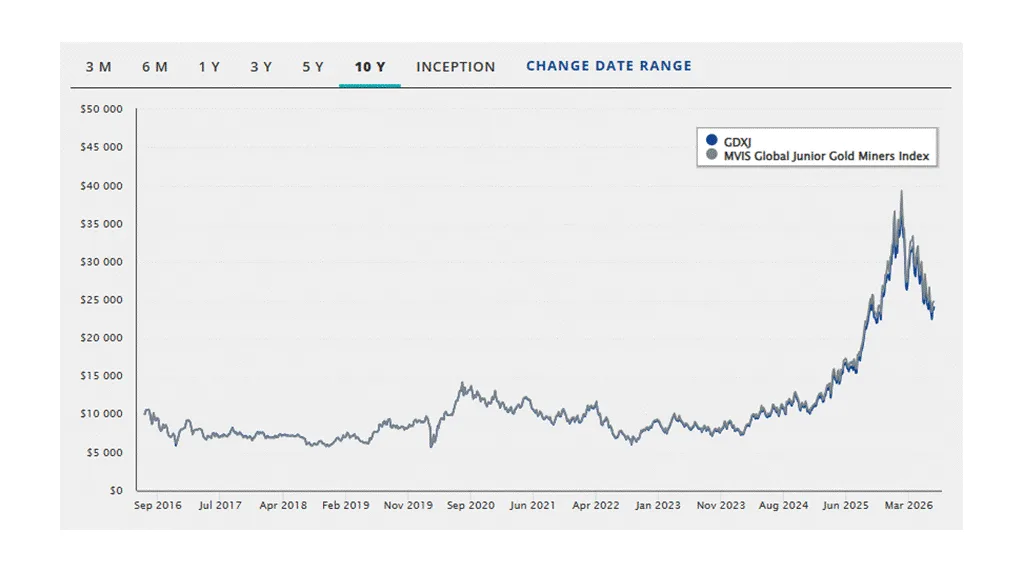
10. VanEck Junior Gold Miners ETF (GDXJ)
The VanEck Junior Gold Miners ETF targets smaller companies involved mainly in gold or silver mining. VanEck reported USD7.10 billion of net assets as of 24 July 2026 as well as gross and net expense ratios of 0.52%.12
Junior miners can carry exploration, financing, construction, dilution, single-asset, and jurisdiction risks in addition to gold-price and equity-market risk. Their shares may move more sharply than bullion in either direction. As such, GDXJ is often perceived as a higher-risk equity exposure, not a low-volatility gold holding.
Which Gold ETF Has the Lowest Expense Ratio?
At 0.09%, IAUM has the lowest stated sponsor fee among the 10 products compared. GLDM follows at 0.10%. Among the other physical-gold products, SGOL, BAR, and AAAU cluster around 0.17% to 0.18%, while IAU and OUNZ charge 0.25%, and GLD charges 0.40%. GDX and GDXJ cost more because they are diversified equity portfolios rather than passive bullion trusts.
That being said, the lowest expense ratio is not always the lowest total cost. A frequent trader may place greater weight on bid-ask spreads, order-book depth, and market impact. A long-term investor making few transactions may place more weight on the recurring annual fee and tracking difference. Brokerage commissions, custody, tax, and currency conversion can also change the comparison.
The following hypothetical example assumes a $100,000 holding, no change in the gross value of gold or the underlying portfolio, and one fee deduction at the end of each year for 10 years. It ignores spreads, commissions, tax, tracking, distributions, fee waivers, and changes in expense ratios. Gold ETF traders and investors should note that it is an illustration of fee mechanics, not an expected result.
| Annual Fee | Illustrative 10-Year Ending Value (Approx. value) | Illustrative Fee Drag (Approx. value) |
| 0.09% | $99,104 | $896 |
| 0.10% | $99,004 | $996 |
| 0.17% | $98,313 | $1,687 |
| 0.25% | $97,528 | $2,472 |
| 0.40% | $96,071 | $3,929 |
| 0.52% | $94,920 | $5,080 |
Vantage Pro Tip: Compare the fee over the expected holding period, then add the round-trip spread and any brokerage or currency costs. A lower annual fee can be outweighed by higher transaction costs when a position is held briefly.
Do Gold ETFs Pay Dividends?
Some gold mining ETFs pay dividends, but physically backed gold trusts generally do not. Gold bullion does not produce revenue, interest, or a dividend. Physical trusts must instead sell or transfer small amounts of gold to meet sponsor fees and expenses, which gradually reduces the gold represented by each share.
GLD, IAU, GLDM, IAUM, SGOL, AAAU, BAR, and OUNZ are primarily designed to track gold after costs. Investors in those products depend mainly on changes in the gold price and the relationship between market price and net asset value. They should not select a physical gold ETF for an income objective.
GDX and GDXJ may make distributions because their underlying mining companies can pay dividends. Those payments depend on company cash flows, board decisions, capital needs, commodity prices, and portfolio changes. The gold ETF’s distribution can therefore rise, fall, or disappear, and a high trailing yield can accompany a declining share price.
| Gold ETF Type | Typical Distribution Pattern | Main Return Drivers |
| Physical-gold trust | Usually no dividend or regular distribution | Gold price less fees, tracking, and trading costs |
| Major-miner ETF | May distribute income if portfolio companies pay dividends | Gold price, margins, operations, equity markets, and distributions |
| Junior-miner ETF | May distribute income, often with less predictability | Exploration, financing, development, gold price, equity markets, and distributions |
Investors comparing dividend income should assess total return rather than yield alone. A distribution is not an additional return if the fund’s net asset value falls by a corresponding amount, and no distribution is guaranteed.
Related Article: Gold ETFs vs. Gold Mining ETFs: How Do They Compare?
Which Gold ETFs Are Backed by Physical Gold?
Eight products in this comparison are physically backed: GLD, IAU, GLDM, IAUM, SGOL, AAAU, BAR, and OUNZ. GDX and GDXJ are not backed by bullion because they own shares in mining businesses.
“Physically backed” still requires due diligence. Investors should read how the trust distinguishes allocated and unallocated gold, which entities can act as custodian or subcustodian, where bars are stored, whether a current bar list is published, how audits or inspections work, and what happens if gold is lost or a service provider fails.
• Allocated gold is recorded against identifiable bars, while unallocated balances are contractual claims that may be used temporarily during creation, redemption, or settlement.
• A bar list can improve transparency by reporting bar numbers, refiners, fineness, and weights, but investors should still review the legal rights attached to fund shares.
• Custodian and subcustodian networks can introduce operational and counterparty exposure even when the trust ultimately holds physical metal.
• Retail redemption is usually unavailable because only authorised participants can create or redeem large baskets; OUNZ is a notable exception with a separate delivery process.
• Trust expenses reduce the amount of gold represented per share over time, so the product is not expected to match the spot price before costs indefinitely.
Physical backing does not protect an investor from a fall in gold prices, a widening market discount, disrupted trading, currency movements, or tax liabilities. It simply describes the product’s underlying asset and should not be perceived as a guarantee of capital.
Physical Gold ETFs vs. Gold-Mining ETFs
Physical and mining funds can both appear in a search for the best gold ETFs, but they serve distinct intentions. A physical trust aims to follow bullion after expenses. A mining ETF owns operating companies whose revenues and costs may respond unevenly to gold.
| Factor | Physical Gold ETF or Trust | Gold-Mining ETF |
| Underlying asset | Gold bullion held through custodians | Shares in mining, royalty, and streaming companies |
| Primary driver | Gold price after fees and tracking | Gold price plus margins, operations, financing, and equity sentiment |
| Income | Usually none | Possible distributions, not guaranteed |
| Volatility | Can be substantial | Often higher because company risks add to gold-price risk |
| Diversification | Single-commodity exposure | Portfolio of companies, but concentrated in one industry |
| Key additional risks | Custody, structure, tracking, market discount, and liquidity | Operational, management, reserve, jurisdiction, debt, and share-market risks |
| Typical comparison use | Directer bullion-price exposure | Equity exposure with operational sensitivity to gold |
For more information on these structural differences, read Vantage Markets’ comparison guide to gold ETFs versus gold-mining ETFs.
How Should You Choose Between Gold ETFs?
A useful selection process starts with the required exposure and then tests whether the product’s costs and structure support it. The ticker should be the final step, not the first.
1. Define the Exposure
Decide whether the objective is bullion-price exposure, major-miner equities, junior miners, income, options access, or eventual delivery. A physical trust cannot reproduce miner dividends, while a mining fund cannot provide direct ownership of bullion.
2. Match the Fee to the Holding Period
Annual fees compound through time, so small differences matter more over a long holding period. Spreads and market impact matter more when trading is frequent or the intended holding period is short. Compare both rather than using the expense ratio in isolation.
3. Check Live Liquidity
Review the current bid and offer, quoted depth, recent volume, and premium or discount to net asset value (NAV). Use limit orders where appropriate and avoid assuming that a large AUM figure guarantees the same execution quality at every time of day.
4. Read the Custody and Redemption Terms
For physical products, identify custodians, subcustodians, vault locations, bar lists, audit practices, and basket sizes. If physical delivery matters, confirm the current minimum, available formats, fees, processing, shipping, insurance, and jurisdictional restrictions.
5. Compare Income and Company Risk
If distributions matter, examine the mining fund’s trailing and current distribution data alongside total return and portfolio quality. Do not treat a miner dividend as bond-like income because commodity prices and company boards can change it.
6. Account for Currency, Tax, and Access
A US-listed ETF trades in US dollars, but the investor’s economic result may also reflect home-currency movements and conversion costs. Tax treatment can differ between bullion trusts, equity ETFs, accounts, and countries. It’s best to obtain qualified advice for personal tax questions.
7. Review Concentration and Loss Capacity
Gold may diversify some portfolios, but a gold-only product is itself concentrated. Set a position size that remains tolerable during a large drawdown, and consider how the holding interacts with cash, bonds, shares, property, and other commodities.
Investors still deciding between bullion, funds, shares, or derivatives can check out Vantage Markets’ guide to investing in gold for a more in-depth read.
Are Gold ETFs Available in Every Country?
No. The 10 products in this guide are US-listed, and access depends on the investor’s broker, residence, regulatory classification, and local rules. Some brokers restrict US exchange-traded products for certain clients, while local markets may offer different gold ETFs, exchange-traded commodities, mutual funds, or savings products.
A foreign listing can also introduce US-dollar dealing, conversion charges, withholding or estate considerations, local reporting obligations, and market-hours differences. These issues may matter more than a few basis points of annual fee. The fund with the lowest US expense ratio may not be the lowest-cost or most accessible route after local considerations.
Investors should confirm that the security can be bought in their account, read the local product disclosure, and obtain tax or legal advice where required.
Can Gold ETF CFDs Be Traded With Vantage Markets?
Eligible clients may be able to trade contracts for difference (CFDs) linked to selected gold ETFs through Vantage Markets, such as GLD and GDX. Product availability varies by entity, platform, and jurisdiction, so the current instrument list and contract specification should be checked before any trade.
A gold ETF CFD does not transfer ownership of ETF shares, bullion, or mining companies. Instead, it’s an agreement with the CFD provider to exchange the difference between opening and closing prices. A trader can take long or short market exposure, but note that either direction can lose money.
| Feature | Buying a Conventional Gold ETF | Trading a Gold ETF CFD |
| Ownership | Owns fund or trust shares through a broker | No ownership of the underlying ETF or gold |
| Upfront amount | Usually the full purchase value unless separate margin is used | Margin controls a larger notional position |
| Market direction | A conventional long holding gains value mainly when its price rises | Long and short positions are available |
| Typical costs | Expense ratio, spread, brokerage, custody, tax, and currency | Spread, possible commission, overnight funding, and currency |
| Holding period | Often used for medium- or long-term exposure | Often used for shorter-term tactical trading |
| Additional risks | Fund, market, custody, tracking, and liquidity risk | Leverage, margin close-out, execution, funding, and counterparty risk |
For CFDs, leverage is a double-edged feature because it magnifies both potential gains and losses relative to the margin deposited. Spreads may widen, overnight funding can accumulate, and stop-loss orders may execute at a different price during gaps or fast markets. A CFD should therefore not be treated as a lower-cost long-term replacement for an unleveraged ETF.
Vantage Markets’ CFDs versus ETFs guide explains how ownership, leverage, and funding differ. Traders can also review ETF mechanics in our ETF trading guide.
A Vantage Demo Account can be used to practise platform navigation, position sizing, and margin monitoring with virtual funds. Demo conditions cannot fully reproduce live execution, slippage, funding, liquidity, or the behavioural impact of real losses.
The Best Gold ETFs Would Be the Ones That Are Best For Your Goals
For many traders and investors, GLD may stand out where scale and options matter, IAUM or GLDM where stated annual fees receive greater weight, OUNZ where a delivery route matters, and GDX or GDXJ where the intention is mining-equity exposure rather than bullion.
Yet, none of those observations makes a gold ETF universally best. Recheck the latest prospectus, fee, assets, spread, distribution history, custody terms, and access before deciding. Then, assess position size against the possibility of a large gold or equity-market decline.
For shorter-term market analysis, traders can explore the Vantage Markets economic calendar and practise with a Vantage Demo Account before considering live leveraged products. Educational tools do not remove market risk or replace independent advice.
FAQs
What is the best gold ETF in 2026?
There is no universal ‘best’ gold ETF in 2026. GLD offers the greatest scale in this comparison, IAUM has the lowest stated sponsor fee, OUNZ has a physical-delivery process, and GDX or GDXJ provide mining-equity exposure. The appropriate comparison would depend on the investor’s or trader’s required exposure, holding period, liquidity, jurisdiction, costs, and risk tolerance.
Which gold ETF has the lowest expense ratio?
As of July 2026, IAUM has the lowest stated sponsor fee in this comparison at 0.09%, followed by GLDM at 0.10%. IAUM filings also describe a temporary fee waiver, so investors should verify the currently effective rate and expiry in the latest prospectus. That said, a lower fee does not automatically mean a lower total cost after spreads, brokerage, tax, and currency conversion.
Which gold ETF has the highest trading volume?
GLD is generally the highest-volume and deepest-market physical gold product among the funds compared, and it also offers listed options. Daily volume and spreads change, so live market data should be checked before dealing. IAU is another large and actively traded physical-gold trust, while smaller funds may still offer adequate liquidity for modest orders.
Which gold ETFs are backed by physical gold?
GLD, IAU, GLDM, IAUM, SGOL, AAAU, BAR, and OUNZ are physically backed products in this comparison. GDX and GDXJ hold mining-company shares instead of bullion. Physical backing does not remove gold-price, custody, structural, liquidity, or currency risks.
Do gold ETFs pay dividends?
Physical gold trusts generally do not pay dividends because bullion produces no income. Gold-mining ETFs, such as GDX and GDXJ, may make distributions when portfolio companies pay dividends, but the amount is variable and not guaranteed. Investors should compare total return and risk rather than selecting on trailing yield alone.
Is a gold ETF still a good investment?
A gold ETF may support diversification or gold-price exposure, but it’s not necessarily suitable for every objective or investor. Gold can fall, physical trusts produce no regular income, and mining ETFs can introduce company and equity-market risk. Suitability depends on personal circumstances, portfolio role, costs, time horizon, and capacity for loss.
Can retail investors redeem gold ETF units for bullion?
Retail investors usually cannot redeem ordinary physical gold ETF shares directly for bullion because creations and redemptions occur in large baskets through authorised participants. OUNZ offers a separate delivery process, subject to its application rules, fees, available products, shipping, insurance, and jurisdictional limits. Investors should read the current delivery documents before relying on that feature.
RISK WARNING: CFDs are complex financial instruments and carry a high risk of losing money rapidly due to leverage. You should ensure you fully understand the risks involved and carefully consider whether you can afford to take the high risk of losing your money before trading.
Disclaimer: The information is provided for educational purposes only and doesn’t take into account your personal objectives, financial circumstances, or needs. It does not constitute investment advice. We encourage you to seek independent advice if necessary. The information has not been prepared in accordance with legal requirements designed to promote the independence of investment research. No representation or warranty is given as to the accuracy or completeness of any information contained within. This material may contain historical or past performance figures and should not be relied on. Furthermore estimates, forward-looking statements, and forecasts cannot be guaranteed. The information on this site and the products and services offered are not intended for distribution to any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation.
References
- “Gold ETF Flows: June 2026 – World Gold Council” https://www.gold.org/goldhub/research/gold-etfs-holdings-and-flows/2026/07. Accessed on 28 July 2026.
- “SPDR Gold Shares (GLD) – State Street Investment Management” https://www.ssga.com/us/en/individual/etfs/spdr-gold-shares-gld. Accessed on 28 July 2026.
- “iShares Gold Trust (IAU) – iShares” https://www.ishares.com/us/products/239561/ishares-gold-trust. Accessed on 28 July 2026.
- “SPDR Gold MiniShares (GLDM) – State Street Investment Management” https://www.ssga.com/us/en/individual/etfs/spdr-gold-minishares-gldm. Accessed on 28 July 2026.
- “iShares Gold Trust Micro (IAUM) – iShares” https://www.ishares.com/us/products/306979/fund. Accessed on 28 July 2026.
- “iShares Gold Trust Micro Annual Filing – iShares” https://www.ishares.com/us/literature/annual-filings/iaum-1231.pdf. Accessed on 28 July 2026.
- “abrdn Gold ETF Trust Form 10-Q for 31 March 2026 – U.S. Securities and Exchange Commission” https://www.sec.gov/Archives/edgar/data/1450923/000199937126010359/sgol-10q_033126.htm. Accessed on 28 July 2026.
- “Goldman Sachs Physical Gold ETF Fact Sheet – Goldman Sachs Asset Management” https://am.gs.com/public-assets/documents/562374a8-24d6-11ef-870d-cd3a62c33790. Accessed on 28 July 2026.
- “GraniteShares Gold Trust Form 10-Q for 31 March 2026 – GraniteShares” https://graniteshares.com/media/5tmogwms/bar-10q-march-2026.pdf. Accessed on 28 July 2026.
- “VanEck Merk Gold ETF (OUNZ) – VanEck” https://www.vaneck.com/us/en/investments/merk-gold-trust-etf-ounz/. Accessed on 28 July 2026.
- “VanEck Gold Miners ETF (GDX) – VanEck” https://www.vaneck.com/us/en/investments/gold-miners-etf-gdx. Accessed on 28 July 2026.
- “VanEck Junior Gold Miners ETF (GDXJ) – VanEck” https://www.vaneck.com/us/en/investments/junior-gold-miners-etf-gdxj/overview/. Accessed on 28 July 2026.